

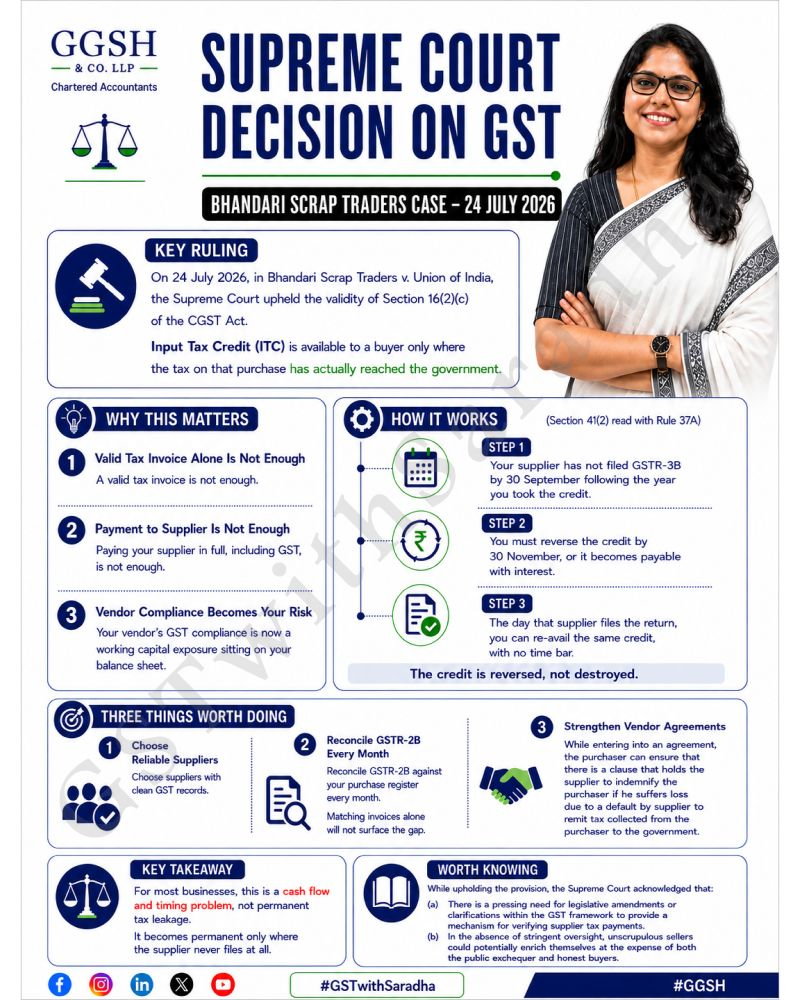
The Supreme Court’s dismissal of the SLP in Bhandari Scrap Traders v. Union of India & Ors. has brought significant attention to the operation of Section 16(2)(c) of the CGST Act and the impact of supplier tax compliance on the recipient’s Input Tax Credit (ITC).
At its core, the issue is straightforward:
Can a recipient claim ITC when the supplier has not actually discharged the tax payable to the Government?
The decision, however, goes beyond simply answering this question.
The Background: Section 16(2)(c)
Section 16(2)(c) of the CGST Act makes payment of the tax charged on the supply to the Government, either in cash or through utilisation of ITC, one of the conditions for claiming ITC.
This creates an important practical issue for genuine purchasers.
A recipient may have:
- A valid tax invoice;
- Paid the supplier;
- Actually received the goods or services; and
- Complied with other applicable requirements.
Yet, if the supplier fails to discharge the corresponding tax liability, the recipient’s ITC position may still be affected.
This was the central concern examined by the Gujarat High Court.
The Quest Merchandising Argument
One of the important arguments considered by the Gujarat High Court was whether the reasoning adopted by the Delhi High Court in Quest Merchandising could be applied to the GST regime.
In Quest Merchandising, the Delhi High Court had examined the relevant provisions under the erstwhile DVAT regime and considered the difficulties faced by genuine purchasers in independently verifying whether the supplier had actually discharged its tax liability.
A similar line of reasoning was subsequently considered by the Tripura High Court in Sahil Enterprises in the context of Section 16(2)(c) of the CGST Act.
The underlying concern was simple:
How can a genuine purchaser ensure compliance with a condition that substantially depends upon the conduct of the supplier?
Why the Gujarat High Court Took a Different View
The Gujarat High Court did not accept that the reasoning in Quest Merchandising could simply be transplanted into the GST framework.
The Court examined the GST legislation as a complete and interconnected statutory framework.
In particular, it considered the relationship between:
- Section 16(2)(c);
- Section 41(2); and
- Rule 37A.
These provisions contemplate mechanisms for dealing with situations where the supplier has not discharged the tax liability, including reversal of ITC and subsequent re-availment when the relevant tax is ultimately paid.
Therefore, according to the Court, Section 16(2)(c) cannot be examined in isolation from the wider GST mechanism.
The Destination-Based Nature of GST
The Court also considered the fundamental nature of GST as a destination-based consumption tax.
The GST framework, including the IGST mechanism, involves the movement and settlement of tax revenues between jurisdictions based on the place of supply.
Allowing ITC merely on the strength of an invoice, without the corresponding tax actually reaching the Government, could have implications for the revenue of the State in which the supply is ultimately consumed.
This was an important factor in understanding why the statutory condition under Section 16(2)(c) could not simply be disregarded.
Can the Provision Be “Read Down”?
Another significant issue was the doctrine of reading down.
The argument in such cases is generally that a statutory provision should be interpreted narrowly when its literal operation creates an unfair or constitutionally problematic consequence.
However, the Gujarat High Court emphasised that reading down is not a tool that can be used merely because a statutory provision creates hardship or inconvenience.
It becomes relevant where giving the provision its plain meaning would result in a genuine constitutional infirmity.
According to the Court, the GST framework already contains mechanisms to address supplier default and provide for corrective action.
Therefore, the existence of difficulties faced by genuine purchasers was not, by itself, sufficient to invalidate or read down Section 16(2)(c).
ITC Is a Statutory Benefit
The judgment also reiterates an important principle in indirect taxation:
ITC is not an unconditional or vested right.
It is a statutory benefit available subject to fulfilment of the conditions prescribed by the legislation.
Consequently, equitable considerations or the fact that a purchaser acted in good faith cannot, by themselves, override an express statutory condition.
This does not mean that the difficulties faced by genuine taxpayers are insignificant.
In fact, the Court acknowledged those concerns.
But the solution, in the Court’s view, lies in strengthening the GST system and its administrative mechanisms rather than rewriting the statutory condition through judicial interpretation.
The Court’s Concern for Genuine Purchasers
Importantly, the judgment did recognise the practical difficulties that bona fide purchasers may face when their ITC is affected because of supplier default.
The Court urged the Government to consider mechanisms such as:
- Real-time verification of supplier tax payments;
- Stronger recovery mechanisms against defaulting suppliers; and
- Measures that reduce the disproportionate burden placed on genuine purchasers.
This is significant because the Court recognised the gap between the legal condition for ITC and the practical ability of a recipient to monitor a supplier’s tax compliance.
What Does This Mean for Businesses?
The decision reinforces an important practical reality:
Your supplier’s GST compliance can directly affect your ITC position.
A business should therefore not stop its due diligence at merely collecting an invoice.
The following become increasingly important:
1. Verify Supplier Details
Ensure that suppliers are properly registered and their GST details are consistent with the transaction.
2. Reconcile GSTR-2B Regularly
Regular reconciliation can help identify mismatches and potential supplier-side compliance issues at an early stage.
3. Monitor Vendor Compliance
For significant vendors, businesses should consider periodic monitoring of return filing and GST compliance.
4. Maintain Complete Transaction Evidence
Invoices, purchase orders, payment records, delivery documents and proof of receipt of goods or services should be maintained systematically.
5. Consider Contractual Safeguards
Commercial agreements with suppliers can include appropriate GST compliance obligations and mechanisms for addressing tax or ITC-related consequences arising from supplier default.
The Larger Lesson
The Bhandari Scrap Traders decision highlights an uncomfortable but important reality of the GST system.
A transaction may be genuine.
The purchaser may have paid the supplier.
The goods or services may have actually been received.
Yet the recipient’s ITC position can still be affected by the supplier’s failure to discharge the corresponding tax liability.
Therefore, supplier due diligence is no longer merely a procurement or accounting function. It can directly become an ITC risk-management function.
For businesses, the message is clear:
A valid invoice is important. Payment is important. Receipt of goods or services is important. But supplier compliance can complete – or affect – the ITC story.
The transaction may be between you and your supplier.
But under the GST framework, the ITC exposure can travel with your supplier too.
Case Reference
Bhandari Scrap Traders v. Union of India & Ors.
The Supreme Court’s dismissal of the SLP has left the Gujarat High Court’s reasoning concerning Section 16(2)(c) of the CGST Act undisturbed.
