The 15-Month FEMA Window Is Gone – Even Before It Begins

RBI changes the 2026 Export & Import Regulations just days before they come into force

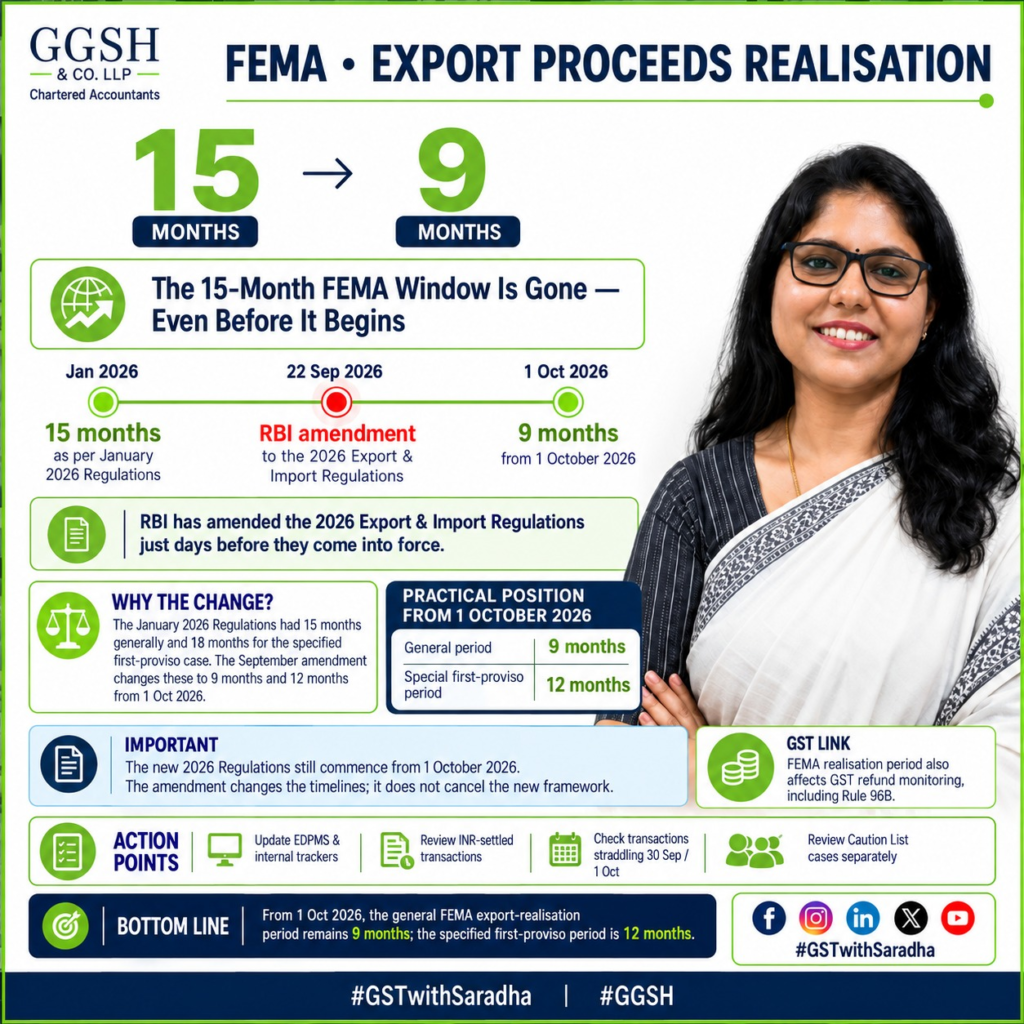
THE UPDATE IN ONE LINE The 2026 Regulations originally provided a 15-month general export-realisation period and an 18-month period in the specified case. RBI has now amended these to 9 months and 12 months respectively, with effect from 1 October 2026.

From our earlier article to the latest update

In our earlier article, we tracked the unusual journey of India’s export-realisation timeline: 9 months → 15 months → 9 months → and then, seemingly, back to 15 months from 1 October 2026.

That last step has now changed. Just days before the new Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 were scheduled to come into force, the Reserve Bank of India amended them.

The result is significant: the 15-month realisation period that was written into the January 2026 Regulations will not become the operative general timeline from 1 October 2026.

There is another important change for the specified transactions involving INR settlement: the special 18-month period has been reduced to 12 months.

What changed this time?

RBI Notification No. FEMA 23(R)/(1)/2026-RB dated 22 September 2026 amends the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026. The amendment comes into force on 1 October 2026 — the same date on which the principal 2026 Regulations commence.

Part of Regulation 5January 2026 RegulationsFrom 1 October 2026
General realisation period15 months9 months
Special period under the first proviso18 months12 months

So, was the 15-month period ever really available?

The January 2026 Regulations had prescribed 15 months for the general realisation period, with 18 months under the specified first proviso. However, those Regulations were notified to commence only from 1 October 2026.

Before that commencement date arrived, RBI issued the September amendment. Therefore, businesses should not plan post-1 October 2026 exports on the basis of the original 15-month timeline.

THE PRACTICAL POSITION FROM 1 OCTOBER 2026 General period: 9 months
Special first-proviso period: 12 months

The FEMA clock has come full circle

The latest amendment makes the timeline we discussed in our earlier article even more relevant.

Period / EventPosition
20169 months becomes the standard timeline.
2020RBI introduces flexibility to specify a different period from time to time.
April 2020Temporary COVID-related extension to 15 months.
November 2025General period moves from 9 → 15 months.
June 2026The period comes back from 15 → 9 months.
January 2026 RegulationsA new framework is notified with 15 months / 18 months, scheduled for October.
September 2026Before that framework starts, RBI changes it to 9 months / 12 months.
1 October 2026The new Regulations commence — but with the shorter timelines.

But the new 2026 Regulations are still important

It would be a mistake to read this amendment as simply ’15 months changed to 9 months’. The larger 2026 framework still comes into force from 1 October 2026.

The September notification changes specific provisions of the January framework; it does not cancel the new Regulations altogether.

This means exporters still need to transition from the 2015 Regulations to the 2026 Regulations, while applying the amended timelines. The practical exercise is therefore not simply to replace ’15’ with ‘9’ in an Excel sheet. It is to understand which parts of the new framework apply to each transaction from 1 October onwards.

What about exporters already on the Caution List?

The September amendment also addresses a specific transition issue. Exporters who are on the RBI Caution List as on 30 September 2026, pursuant to orders issued under the 2015 Regulations, will continue to be governed by the relevant order until they are removed from the Caution List.

This is an important transition provision. The move to the new Regulations does not automatically erase an existing Caution List position.

One more important change: the role of AD Banks

The September notification also introduces a new Regulation 20 – Powers to Authorised Dealers.

Under this provision, Authorised Dealers can handle certain export, import and merchanting-trade transactions undertaken before 1 October 2026 which previously required RBI approval under the 2015 framework and the relevant Master Directions.

For businesses, this reinforces an important point: the transition is not simply ‘old Regulations end → new Regulations start’. Certain transactions originating under the earlier framework can continue to require regulatory handling after the transition.

And what does this mean for GST refunds?

This is where the September notification connects directly back to the issue discussed in our earlier article.

The FEMA realisation period is not an isolated compliance number. Several GST and export-benefit provisions refer to the period permitted under FEMA.

For example, Rule 96B of the CGST Rules links the recovery of refund amounts to non-realisation of export proceeds within the period allowed under FEMA, including any permitted extension.

THE LINK TO GST The FEMA clock is also a GST monitoring clock. With the general FEMA period continuing at nine months from 1 October 2026, businesses should not build refund-monitoring systems around the 15-month period that appeared in the original January 2026 Regulations.

What should exporters do now?

  1. Keep 9 months as the primary planning period – For exports falling under the amended Regulation 5 framework from 1 October 2026, the general period is 9 months. Do not carry forward the earlier assumption of 15 months.
  2. Revisit INR-settled transactions – The special period originally stated as 18 months has now been reduced to 12 months. Identify the transactions covered by this proviso.
  3. Update EDPMS and internal trackers – Update export-realisation trackers, EDPMS monitoring, customer credit-period reviews, GST refund monitoring, FEMA exception reports and management dashboards.
  4. Do not discard the old transaction trail – Exports and regulatory approvals straddling 30 September / 1 October 2026 should be reviewed based on the applicable framework and transaction date.
  5. Review Caution List cases separately – If an exporter is covered by an existing Caution List order as on 30 September 2026, that order continues until removal from the list.

The bigger lesson from the FEMA clock

Our earlier article asked: ‘Which FEMA clock is actually ticking?’ The latest notification makes that question even more relevant.

In January, businesses were preparing for a new framework that appeared to provide a longer realisation window. In June, the existing framework had already tightened back to nine months. And now, in September, RBI has amended the incoming framework itself — before it begins — to retain nine months as the general period.

The important takeaway for exporters is therefore not simply that the deadline is nine months. It is that the FEMA realisation period should not be treated as a permanently fixed number.

For finance and compliance teams, the date of export, the applicable regulation and the transaction structure all need to be looked at together.

A simple timeline to remember

PeriodPosition
Before 13 Nov 20259 months under the then-applicable framework
13 Nov 2025 – 4 Jun 202615 months
5 Jun 2026 – 30 Sep 20269 months
From 1 Oct 20269 months under the amended 2026 Regulations
Special first-proviso period from 1 Oct 202612 months
THE BOTTOM LINE 1 October 2026 still marks the beginning of the new FEMA Export & Import Regulations, 2026. But the expected 15-month general realisation period will not come into operation. The amended framework keeps the general period at 9 months and the specified first-proviso period at 12 months.

Sources

  • RBI Notification No. FEMA 23(R)/(1)/2026-RB dated 22 September 2026 – Foreign Exchange Management (Export and Import of Goods and Services) (Amendment) Regulations, 2026.
  • FEMA 23(R)/2026-RB dated 13 January 2026 – Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026.
  • Official Gazette publication dated 24 September 2026.
  • CGST Rules, including Rule 96B, for the linkage between export refund recovery and the period allowed under FEMA.

GGSH Disclaimer

This article is intended for informational purposes only and does not constitute legal, tax, FEMA or professional advice. Readers should evaluate the applicability of the discussed provisions to their specific facts and seek professional advice before acting on any matter discussed herein. GGSH & Co. LLP shall not be liable for any action taken or not taken based on this publication.
Stock Transfer Without E-Way Bill: Can Section 129 Penalty Still Apply?

A business may move its own goods from one premises to another.

Same entity. Same GSTIN. No customer. No consideration.

There is movement of goods — but is there a “supply” under GST?

And if there is no taxable supply, can a tax-linked penalty under Section 129 be imposed merely because the e-way bill was not generated?

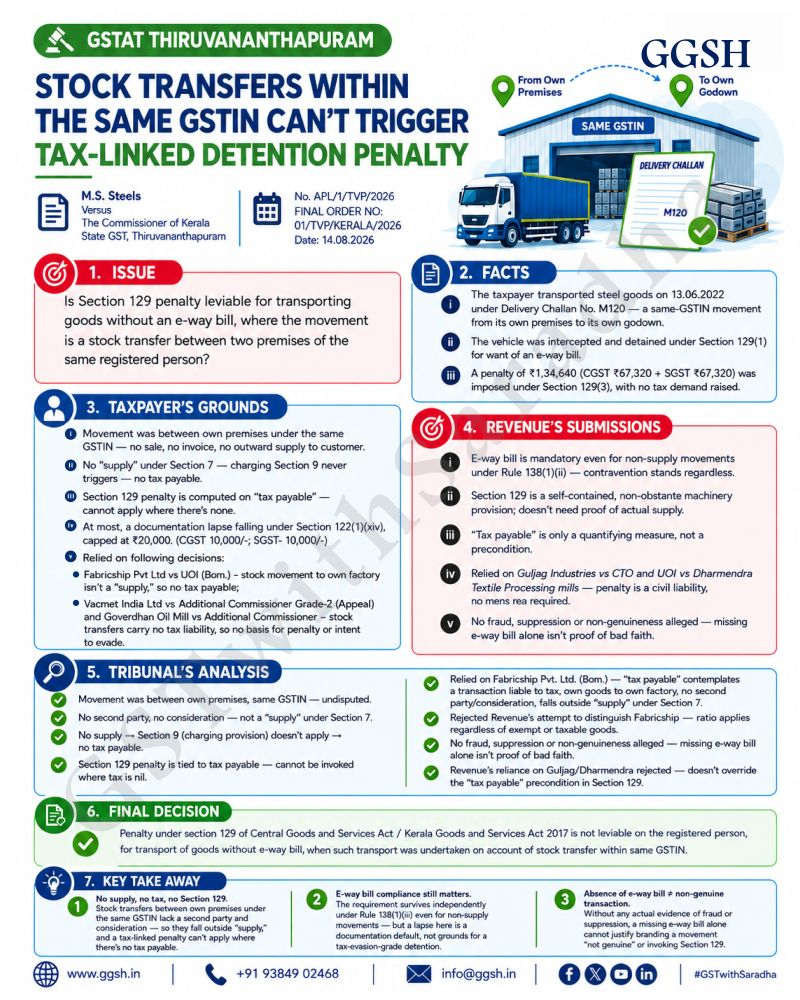
This question came before the GSTAT, Thiruvananthapuram Bench in M.S. Steels v. Commissioner of Kerala State GST, Thiruvananthapuram.

The Tribunal’s decision draws an important distinction between an e-way bill compliance requirement and the tax-linked consequences of a contravention.

The Facts of the Case

M/s M.S. Steels, a partnership firm dealing in steel goods, transported goods from its own premises to its own godown.

Both locations were covered under the same GSTIN, making the movement an internal stock transfer.

The goods were accompanied by a Delivery Challan, but no e-way bill was available during transportation.

The vehicle was intercepted and the goods were detained under Section 129.

A penalty of ₹1,34,640 was imposed under Section 129(3), comprising ₹67,320 CGST and ₹67,320 SGST.

Importantly, no tax demand was raised. The penalty was imposed in connection with the absence of the e-way bill.

The Core Question

The Tribunal considered whether Section 129 penalty could be imposed when the movement itself did not constitute a taxable supply.

Under GST, tax under the charging provision arises on a supply.

Here, the goods were being moved between premises belonging to the same registered person under the same GSTIN. There was no customer, no transfer to another person and no consideration.

On these facts, the Tribunal treated the movement as a stock transfer rather than a taxable supply.

Therefore, there was no tax payable on the movement against which the Section 129 penalty could be computed.

But Was the E-Way Bill Still Required?

Yes.

This is the part that should not be missed.

The Tribunal did not hold that businesses can ignore e-way bill requirements for stock movements.

Rule 138(1)(ii) specifically contemplates movement of goods for reasons other than supply.

Therefore, the absence of an e-way bill can still constitute a compliance breach.

The Tribunal’s distinction was between:

“Was an e-way bill required?”

and

“Does that breach justify a Section 129 tax-linked penalty?”

Those are two different questions.

Why Section 129 Became the Critical Issue

Section 129 operates in the context of detention, seizure and release of goods and links the applicable penalty to the tax payable on the goods.

In a genuine same-GSTIN stock movement where there is no taxable supply, the Tribunal found that there was no tax payable on the movement.

Consequently, a penalty calculated by notionally applying the GST rate to the value of the goods could not be sustained under Section 129.

The Tribunal instead referred to the general documentation-related penalty provision under Section 122(1)(xiv) for the e-way bill/documentation contravention.

The Important Distinction

This case demonstrates why every GST movement case should be analysed in the correct sequence.

1. Identify the transaction

Is it a sale, stock transfer, job work movement, return, exhibition movement or some other movement?

2. Determine whether there is a taxable supply

Does the movement fall within the scope of “supply” under the GST law?

3. Determine the applicable compliance requirement

Even where there is no supply, does Rule 138 require an e-way bill for the particular movement?

4. Identify the correct consequence

If there is a documentation lapse, which statutory provision actually governs the contravention?

This sequence matters because a procedural lapse does not automatically transform a non-taxable movement into a taxable supply.

What Businesses Should Take Away

Businesses regularly moving goods between their own:

  • Warehouses
  • Godowns
  • Branches
  • Manufacturing locations
  • Other business premises

should not treat this ruling as permission to skip e-way bill compliance.

Instead, the practical lesson is to maintain proper documentation even for non-sale movements.

A delivery challan, e-way bill where required, stock records and supporting movement documents can help establish the true nature of the transaction if the goods are intercepted.

At the same time, if proceedings are initiated, taxpayers should examine whether the department has correctly identified:

the nature of the transaction → the existence of tax liability → the applicable penal provision.

The Larger Lesson

The M.S. Steels ruling highlights an important principle in GST proceedings:

A documentation lapse and a taxable supply are not necessarily the same thing.

The Tribunal did not eliminate the e-way bill requirement.

It addressed the consequence of failing to comply with that requirement in a specific factual situation where the movement was an internal stock transfer and no tax was payable.

For businesses, the lesson is therefore simple:

First determine what actually happened.
Then determine whether tax was payable.
Only then determine which penal provision applies.

Because sometimes, answering “What is the transaction?” must come before asking “Which section applies?”

Case Citation

M.S. Steels v. Commissioner of Kerala State GST, Thiruvananthapuram
Appeal No. APL/1/TVP/2026
Final Order No. 01/TVP/KERALA/2026
GSTAT, Thiruvananthapuram Bench
Order dated: 14 August 2026

The Tribunal also relied upon the reasoning in Fabricship Pvt. Ltd. v. Union of India concerning the expression “tax payable” in the context of Section 129.

This article is for general informational purposes only and should not be treated as legal or tax advice. The applicability of the ruling depends on the specific facts, nature of movement and applicable statutory provisions.

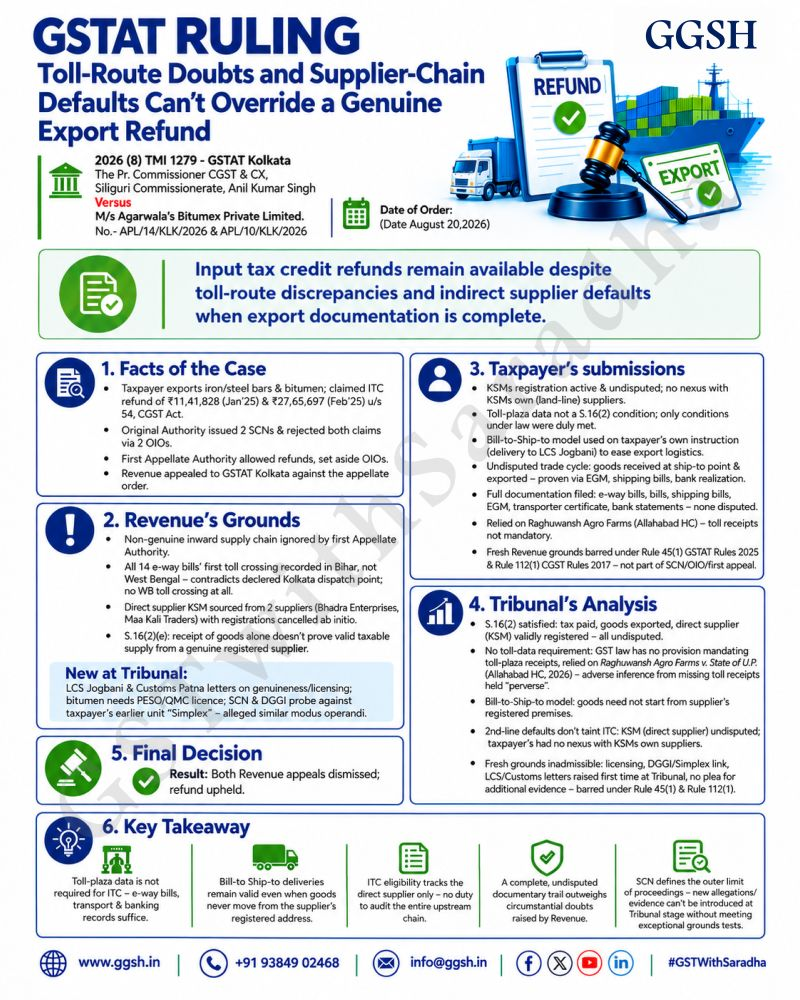
GSTAT Kolkata on ITC & Export Refunds: Can Toll Data and Supplier Defaults Override Genuine Documentation?

🚫 Supplier default.
🚫 Toll-route discrepancies.
🚫 Missing toll data.

These objections are increasingly becoming part of GST proceedings involving Input Tax Credit (ITC) and refund claims.

But an important question arises:

Can such objections, by themselves, be sufficient to deny a genuine transaction when the taxpayer has otherwise produced the documents required under GST law?

A recent ruling of the GSTAT, Kolkata Bench in Pr. Commissioner, CGST & CX, Siliguri Commissionerate v. M/s Agarwala’s Bitumex Pvt. Ltd. provides useful guidance on this issue. The Tribunal decided Revenue appeals APL/10/KLK/2026 and APL/14/KLK/2026 on 20 August 2026.

The Dispute

The case involved refund of accumulated ITC relating to exports.

The Revenue questioned the transactions using, among other things, toll/FASTag movement data and concerns relating to suppliers further up the supply chain.

The taxpayer, however, had documentary evidence supporting the transactions, including tax invoices, e-way bills, transport documents, shipping bills, export documentation and banking records.

The Tribunal examined whether the absence or mismatch of toll-route data could, by itself, establish that the underlying transactions were not genuine.

1. Toll Data Is Not a Statutory Substitute for Documentary Evidence

One of the significant observations was that toll plaza records are not prescribed by GST law as a mandatory condition for establishing movement of goods or claiming ITC/refund.

In this case, the Tribunal considered the broader documentary trail rather than treating toll data in isolation.

This is particularly relevant where the transaction is supported by documents such as:

  • Tax invoices
  • E-way bills
  • Transport documents/bilties
  • Shipping bills
  • Export General Manifest (EGM)
  • Banking records
  • GST returns

The absence of a particular toll record does not automatically establish that goods were never moved. The evidentiary value of toll data must be considered alongside the complete facts and supporting documents.

2. Bill-to-Ship-to Transactions Cannot Be Rejected Merely Because Goods Did Not Move Through the Supplier’s State

The case also involved a Bill-to-Ship-to arrangement.

Under such a commercial structure, the goods may be dispatched directly from a location other than the registered premises of the invoicing supplier.

Therefore, the absence of toll movement through the supplier’s registered State cannot, by itself, establish that the transaction did not take place.

The Tribunal considered the bill-to-ship-to arrangement together with the available transaction and export documentation.

3. Can a Supplier’s Supplier Default Affect the Recipient’s ITC?

Another important issue concerned the second-line or upstream suppliers.

The Revenue raised concerns regarding the registration status of suppliers further up the supply chain.

However, the taxpayer’s direct supplier was a registered entity, and the underlying transaction with the direct supplier was supported by the relevant documentation.

The Tribunal held, in the circumstances of the case, that irregularities concerning the supplier’s supplier could not automatically be used to deny the recipient’s ITC/refund where the taxpayer’s own transaction and the relevant statutory requirements were otherwise established.

This is an important distinction:

A recipient’s entitlement cannot automatically be determined solely by an allegation concerning a party further removed from the taxpayer in the supply chain.

The facts and statutory conditions applicable to the recipient still have to be examined.

4. Can New Grounds Be Introduced at the Tribunal Stage?

There was another significant procedural aspect.

The Revenue sought to rely on grounds that had not formed part of the original proceedings in the manner required.

The Tribunal did not permit the appellate proceedings to become an opportunity to introduce an entirely new factual case that had not been part of the earlier proceedings.

This highlights an important principle in tax litigation:

An appeal is not necessarily an opportunity to introduce entirely new allegations as an afterthought.

The taxpayer should know the case it is required to answer, and the appellate proceedings must operate within the applicable procedural framework.

What Does This Mean for Taxpayers?

The ruling does not mean that toll discrepancies, supplier issues or missing records can never be relevant.

Rather, it reinforces the importance of examining whether the objection:

  1. Is based on an actual statutory requirement;
  2. Is supported by evidence;
  3. Addresses the taxpayer’s own transaction;
  4. Properly considers the complete documentary trail; and
  5. Was actually part of the case made out in the earlier proceedings.

A single data point should not automatically be treated as conclusive proof when the overall transaction is supported by credible statutory and commercial documentation.

Practical Takeaway for Businesses

Businesses facing ITC disputes or export-refund proceedings should maintain a complete documentary trail rather than relying on one category of evidence.

Important records may include:

  • Tax invoices
  • E-way bills
  • Lorry receipts/bilties
  • Purchase and sales records
  • Shipping bills
  • EGM/export records
  • Bank/payment records
  • GST returns
  • Agreements and correspondence
  • Documents supporting the movement and receipt of goods

And when an objection is raised, one question should always be asked:

“Is this actually a statutory requirement, or is it merely being treated as one?”

The Larger Lesson

The Agarwala’s Bitumex ruling is a useful reminder that GST compliance cannot always be reduced to a single data point.

Toll data may be relevant evidence. Supplier compliance may require scrutiny. Documentation must be genuine and complete.

But where the law prescribes particular conditions, the taxpayer should not ordinarily be required to satisfy an additional requirement merely because a particular database, route record or third-party transaction creates a discrepancy.

For businesses with pending ITC disputes or export-refund claims, the decision is therefore worth keeping on the radar.

The real question is not simply whether there is a discrepancy.

The real question is whether that discrepancy legally establishes the allegation being made against the taxpayer.

This article is for general informational purposes and should not be treated as legal or tax advice. The applicability of the ruling depends on the facts, statutory provisions and procedural history of each case.

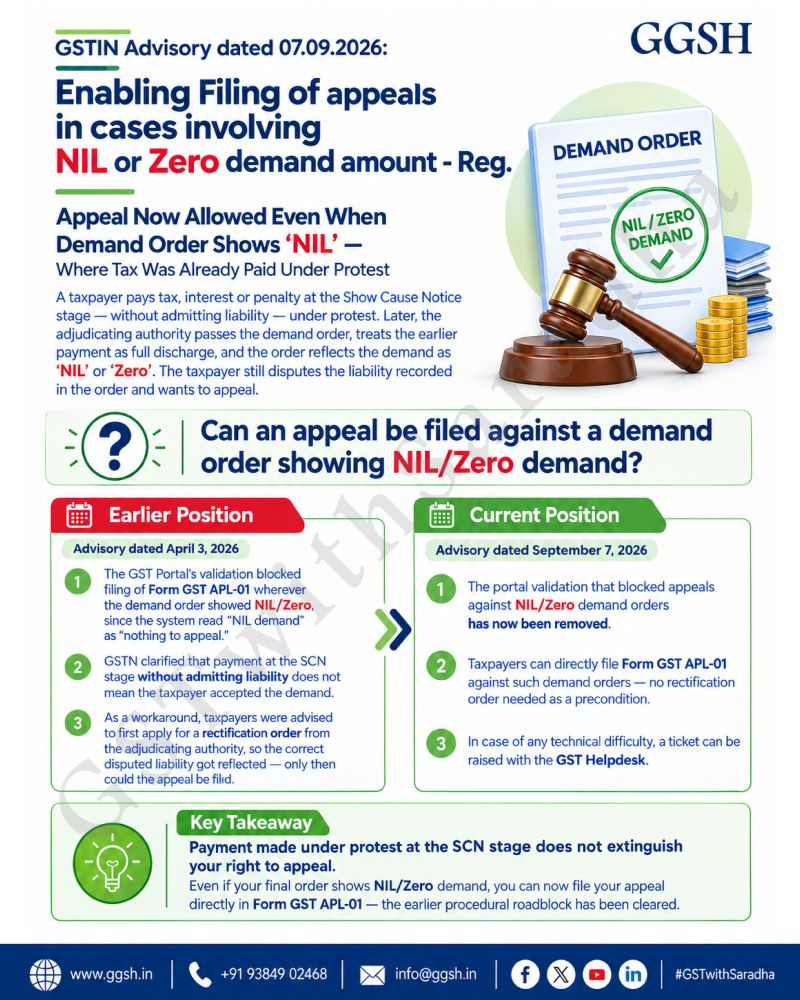
NIL GST Demand Does Not Mean NIL Right to Appeal

You paid the tax under protest.
Perhaps to stop the interest clock or avoid further exposure.

Then the adjudication order arrives — and the demand shown on the portal is NIL or Zero.

But what if you still disagree with the liability determined in that order?

Can you appeal?

Until recently, a technical validation on the GST Portal could make that question surprisingly difficult in practice.

The Problem: Payment Before the Order

A peculiar situation could arise when a taxpayer made payment at the SCN stage, without admitting the underlying liability.

When the adjudication order was subsequently issued, the amount already paid could result in the order reflecting NIL or Zero outstanding demand.

However, the taxpayer could still have a genuine dispute regarding the findings in the order — such as the determination of tax liability, eligibility of an input tax credit, classification, or other issues.

The problem was that the GST Portal’s validation could prevent the taxpayer from filing FORM GST APL-01, because the system saw a NIL/Zero demand.

In other words:

No outstanding demand did not necessarily mean there was nothing to challenge.

What GSTN Has Now Changed

GSTN, through Advisory No. 671 dated 7 September 2026, has addressed this specific portal-level difficulty.

GSTN has removed the earlier validation that restricted appeals where the demand amount was reflected as “NIL” or “Zero”, in cases where a liability dispute exists and payment had been made before issuance of the demand order.

Taxpayers facing such cases are now enabled to file an appeal in FORM GST APL-01 directly. A rectification order is no longer required as a precondition merely to overcome this portal validation.

This is an important distinction between the amount outstanding and the substantive dispute contained in the order.

Why This Matters

A GST order can have consequences beyond the amount currently appearing as payable on the portal.

A taxpayer may disagree with the legal or factual findings recorded in the order even where the monetary demand has already been discharged.

Therefore, the existence of an appealable grievance cannot necessarily be determined simply by looking at whether the portal shows an outstanding balance.

GSTN’s latest change addresses the technical filing barrier and allows the taxpayer to access the appellate mechanism in these specified NIL/Zero-demand situations.

But There Is One Critical Point: Limitation

Removing the portal validation does not automatically extend the statutory time limit for filing an appeal.

Under Section 107(1) of the CGST Act, an appeal to the Appellate Authority is ordinarily required to be filed within three months from the date on which the order is communicated. Section 107(4) permits the Appellate Authority, subject to the statutory conditions, to allow a further period of one month where sufficient cause is established.

Therefore, taxpayers should not interpret the GSTN portal change as a fresh limitation period.

Portal accessibility and statutory limitation are two different issues.

What Should Taxpayers Check?

If you have received an order showing NIL or Zero demand but continue to dispute the findings, review:

  • The date on which the order was communicated
  • The adjudication order and the specific findings being challenged
  • The payment made before issuance of the order
  • Whether the payment was made without admitting liability, wherever applicable
  • Records of any earlier attempt to file the appeal
  • Any GST Portal error or validation that prevented filing
  • The applicable limitation period under Section 107
  • Documents and grounds required for filing FORM GST APL-01

If a technical difficulty continues while filing, GSTN has advised taxpayers to raise a ticket with the GST Helpdesk.

The Larger Principle

NIL demand is not necessarily the same as NIL dispute.

A taxpayer may have already paid an amount, while still maintaining that the underlying liability determined by the department is incorrect.

The GSTN’s September 2026 change is therefore significant from a portal and procedural perspective: the absence of an outstanding demand should no longer, in the specified circumstances, prevent the taxpayer from electronically filing an appeal.

But the next step remains crucial:

Check the limitation. Preserve the evidence. File the appeal on time.

Reference

GSTN Advisory No. 671 dated 7 September 2026
“Enabling Filing of Appeals in Cases Involving NIL or Zero Demand Amount”

Read with the earlier GSTN advisory dated 3 April 2026 concerning difficulties in filing appeals where adjudication orders reflected NIL demand due to prior voluntary payment.

This article is for general information and should not be treated as legal or tax advice. The applicability of the appellate remedy and limitation period should be examined based on the specific order and facts of each case.

Missing Documents Cannot Automatically Make a Genuine Transaction Disappear

In GST proceedings, documentation plays a crucial role in establishing the genuineness of a transaction. However, an important question arises when certain supporting documents are unavailable: Can the absence of one particular document, by itself, be sufficient to disprove an otherwise supported transaction?

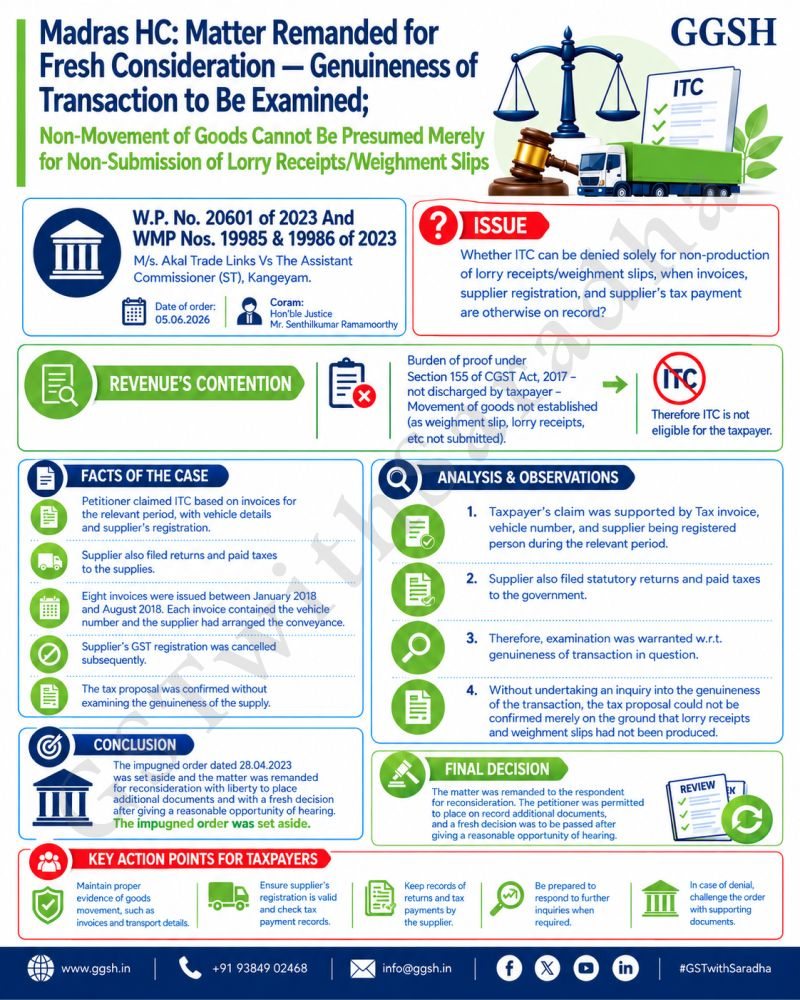
The Madras High Court recently considered this issue in M/s. Akal Trade Links, Rep. by its Partner Sri R. Sangar Ganesh v. The Assistant Commissioner (ST), Kangeyam, W.P. No. 20601 of 2023 & W.M.P. Nos. 19985 & 19986 of 2023, decided on 5 June 2026.

The case concerned a dispute over Input Tax Credit (ITC) where the Department questioned the movement and genuineness of goods primarily because certain transportation-related documents, including lorry receipts and weighment slips, had not been produced.

The Question Before the Court

The taxpayer had several pieces of evidence supporting the underlying transactions, including:

  • Tax invoices
  • Vehicle details
  • A registered supplier
  • Supplier compliance records
  • Evidence that the supplier had filed its returns
  • Evidence that tax had been paid by the supplier

Despite these circumstances, the ITC claim was questioned on the ground that certain transport documents were unavailable and the physical movement of goods had therefore not been sufficiently established.

This brought the issue into focus:

Does the non-production of a particular transport document automatically establish that the underlying transaction was not genuine?

The Court’s Approach

The Court’s approach highlights an important distinction.

The burden of establishing eligibility for ITC does not disappear merely because other evidence exists. A taxpayer is still expected to substantiate the transaction and satisfy the applicable requirements.

However, the examination cannot necessarily stop at the absence of one category of document.

The genuineness of the transaction has to be examined on the basis of the evidence available as a whole.

Therefore, the mere non-production of lorry receipts, weighment slips or similar transport documents cannot, by itself, become the sole basis for concluding that the transaction never took place, particularly where other supporting evidence is available.

This becomes even more significant where the supplier is registered, has reported the transaction in its returns and has discharged the corresponding tax liability.

Why This Matters for ITC Claims

GST assessments often involve examination of multiple interconnected documents.

An invoice may establish the commercial transaction. An e-way bill may support movement of goods. Banking records may establish payment. Supplier returns may provide evidence of reporting and tax compliance. Vehicle details and other records may further strengthen the factual trail.

No single document necessarily exists in isolation.

Therefore, while the absence of a particular document may raise a question requiring explanation, it should not automatically replace the broader examination of the transaction itself.

The real question should be whether the overall evidence establishes the genuineness of the supply and the taxpayer’s entitlement to ITC.

A Similar Question Had Arisen Earlier

The issue also brings to mind the earlier Raghuvansh Agro Farms ruling of the Allahabad High Court, where questions concerning supplier existence, e-way bills, banking transactions and additional transportation-related evidence were considered.

The broader principle emerging from such cases is not that documentation is unimportant.

Rather, it is that documentation must be evaluated in context.

A missing document may be a deficiency. But a deficiency in one document should not necessarily be treated as conclusive proof that the entire transaction is fictitious, particularly when substantial independent evidence supports the transaction.

Practical Takeaway for Businesses

For businesses claiming ITC, the safest approach remains complete and consistent documentation.

Businesses should, wherever applicable, maintain:

1. Tax Invoices
Ensure invoices are properly issued, recorded and reconciled.

2. E-Way Bills
Maintain e-way bill records wherever applicable.

3. Transportation Evidence
Preserve lorry receipts, delivery challans, weighment slips, transporter records and other available evidence relating to movement of goods.

4. Payment Trails
Maintain bank statements and payment records supporting the transaction.

5. Supplier Compliance Records
Where possible, retain evidence supporting the supplier’s registration, return filing and tax compliance.

6. Accounting & Stock Records
Purchase registers, stock records, inward registers and corresponding accounting entries can also help establish the commercial substance of the transaction.

The Larger Lesson

This judgment should not be interpreted as a relaxation of documentation requirements.

Businesses should not treat missing documents casually.

Instead, the decision serves as a reminder of an equally important principle:

The absence of one document should not automatically become the absence of the transaction.

The objective of an assessment should be to determine whether the transaction is genuine by considering the entire evidentiary trail, rather than allowing one missing piece of documentation to conclusively determine the outcome.

For taxpayers, the message is clear:

Be complete in maintaining evidence.
And when that evidence is evaluated, look at the complete picture.

Case: M/s. Akal Trade Links, Rep. by its Partner Sri R. Sangar Ganesh v. The Assistant Commissioner (ST), Kangeyam
W.P. No.: 20601 of 2023 & W.M.P. Nos. 19985 & 19986 of 2023
Court: Madras High Court
Date: 5 June 2026

When Composition Scheme Lapses: How Should GST and ITC Be Determined?

For businesses registered under the Composition Scheme, crossing the prescribed turnover threshold can significantly change the applicable GST treatment. Once the threshold is breached, the benefit of the Composition Scheme ceases and subsequent supplies become taxable under the regular GST framework.

But an important practical question arises:

If supplies have already been made after crossing the threshold, without separately collecting GST from customers, should GST be calculated by applying the tax rate over and above the invoice value?

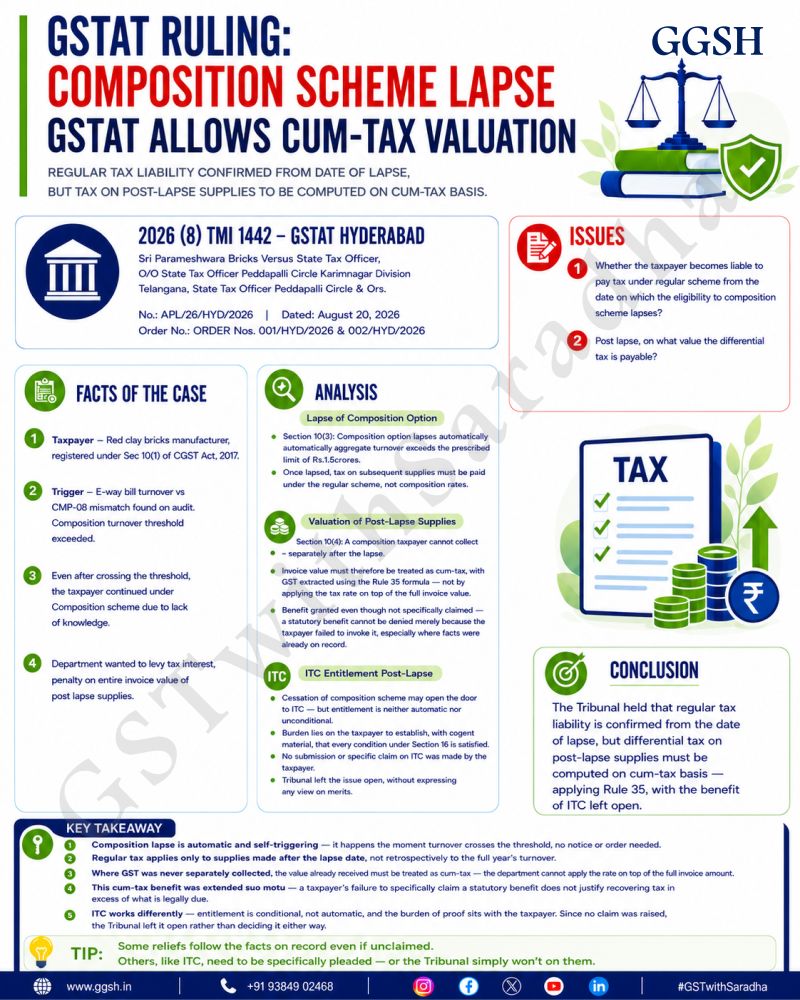
The GSTAT Hyderabad recently examined this issue in Sri Parameshwara Bricks v. State Tax Officer & Ors.

The Issue

The appellant was operating under the Composition Scheme. After crossing the prescribed turnover threshold, the composition benefit ceased to apply and the subsequent supplies became liable to GST under the regular scheme.

However, the taxpayer had already received the invoice amounts from customers without separately collecting GST.

The question before the Tribunal was therefore not merely whether GST was payable, but how the GST liability had to be computed.

Cum-Tax Treatment of the Invoice Value

Under Section 10(4), a person paying tax under the Composition Scheme cannot collect tax from the recipient of supplies.

Considering this restriction and the fact that the amounts had already been received from customers without separately collecting GST, the GSTAT Hyderabad held that the invoice value had to be treated as cum-tax value.

Accordingly, GST was required to be determined by applying the prescribed Rule 35 cum-tax formula, rather than simply calculating GST on top of the entire invoice value.

This distinction is significant.

A tax demand cannot be mechanically increased by treating the amount already received from the customer as an amount exclusive of GST when, in substance, no separate GST had been collected.

Can a Statutory Benefit Be Granted Even If the Taxpayer Did Not Specifically Claim It?

Interestingly, the Tribunal extended the benefit of the cum-tax methodology even though the appellant had not specifically claimed it.

The reasoning was that a taxpayer’s failure to specifically request a statutory benefit cannot justify recovery of an amount higher than the tax legally payable.

In other words, the assessment must ultimately determine the correct statutory liability—not create an excess demand merely because the taxpayer failed to raise a particular argument.

What About Input Tax Credit?

The position regarding ITC was treated differently.

The Tribunal acknowledged that once the Composition Scheme ceases to apply, a taxpayer may potentially become eligible for Input Tax Credit under the regular scheme.

However, such entitlement is not automatic.

The taxpayer must satisfy the applicable conditions under Section 16 and establish its eligibility through proper evidence and compliance.

In this case, the appellants had not made any specific submission or claim seeking ITC.

Consequently, the Tribunal declined to examine the ITC issue and left the question of entitlement open, without expressing any opinion on the merits.

This distinction is particularly important:

Cum-tax relief was considered because the relevant facts were already available before the Tribunal. ITC, however, was not examined because it had neither been specifically claimed nor properly established.

The Key Takeaway

Crossing the turnover threshold changes the taxpayer’s GST treatment, but it does not mean that the tax liability can be calculated without following the prescribed statutory methodology.

At the same time, statutory benefits do not operate identically in every situation.

The case demonstrates two important principles:

1. Tax must be computed according to law.
Where the facts establish that the consideration received was inclusive of tax, the prescribed cum-tax mechanism must be considered.

2. Benefits such as ITC must be specifically claimed and established.
A potential entitlement does not automatically translate into an allowable credit. The taxpayer must satisfy the statutory conditions and discharge the necessary burden of proof.

Ultimately, the case serves as a practical reminder for businesses:

What you don’t claim, establish and argue before the authority may not be examined on your behalf.

Proper documentation, timely compliance and clearly raising every available statutory claim remain essential when a business transitions from the Composition Scheme to the regular GST regime.

Case Citation

Sri Parameshwara Bricks v. State Tax Officer & Ors.
APL/26/HYD/2026
Date: 20 August 2026
2026 (8) TMI 1442 – GSTAT Hyderabad

When a GST Appeal Is Delayed: Can Exceptional Circumstances Still Matter?

text

A statutory deadline is not merely a procedural formality. It determines the period within which a taxpayer can exercise a particular legal remedy.

But what happens when an appeal is filed beyond the prescribed period due to circumstances that are genuine, exceptional and beyond the taxpayer’s control?

This question was considered by the High Court of Judicature for Rajasthan at Jaipur in Bhagwati Industries v. Union of India & Ors.

The Importance of Section 107

Under Section 107 of the CGST Act, a person aggrieved by an order passed by the adjudicating authority is provided a specific statutory period to file an appeal.

The provision also permits a limited extension where the prescribed conditions are satisfied.

Therefore, taxpayers cannot assume that an appeal can be filed at any time merely by approaching the High Court.

Statutory timelines continue to matter.

However, the issue becomes more complex when the taxpayer is unable to pursue the statutory remedy within the prescribed period because of exceptional circumstances.

Where Article 226 Comes Into the Picture

The judgment highlights the distinction between the statutory appellate remedy under Section 107 and the constitutional jurisdiction of the High Court under Article 226 of the Constitution.

Article 226 gives High Courts the power to issue appropriate writs in appropriate circumstances.

This does not mean that Article 226 can routinely be used to bypass statutory limitation periods or replace the appellate mechanism provided under the GST law.

Instead, in exceptional circumstances, the constitutional jurisdiction of the High Court may become relevant where the facts justify judicial intervention.

The key consideration, therefore, is not simply:

“Was the appeal filed late?”

The circumstances behind the delay may also require examination.

Delay Does Not Automatically Mean the End of the Dispute

For a business, a delayed GST appeal can have serious consequences.

An order may remain unchallenged because of circumstances such as genuine difficulties, procedural complications or other factors that prevented the taxpayer from approaching the appellate authority within the available period.

A mechanical approach that looks only at the date may overlook the circumstances in which the delay occurred.

The judgment reinforces the importance of examining the facts behind the delay, particularly when a taxpayer seeks extraordinary relief from the High Court.

A Balanced Legal Approach

The decision should not be understood as saying that GST appeal deadlines are irrelevant.

They are not.

Taxpayers must comply with the statutory framework and pursue their remedies within the prescribed time wherever possible.

At the same time, the existence of a statutory remedy does not necessarily mean that the High Court’s constitutional jurisdiction becomes completely unavailable in every exceptional situation.

The exercise of Article 226 jurisdiction remains discretionary and depends heavily on the facts and circumstances of each case.

Therefore, there is an important balance:

Limitation protects the certainty of legal proceedings.
Exceptional circumstances may justify judicial consideration.

Practical Takeaway for Businesses

Businesses should never allow a GST order to remain unattended merely because they are considering whether to appeal.

If an adverse order is received:

  • Identify the date of communication of the order.
  • Calculate the statutory appeal period immediately.
  • Evaluate whether an appeal under Section 107 is available.
  • Collect documents explaining any delay.
  • Record the circumstances that prevented timely filing.
  • Obtain professional advice before the statutory period expires.
  • If the statutory remedy has been lost, examine whether any exceptional circumstances justify approaching the High Court.

Most importantly, do not assume that an old GST dispute is automatically beyond consideration without examining the facts.

The reason for the delay, the nature of the order, the statutory remedy available and the circumstances surrounding the taxpayer’s inability to pursue that remedy can all be relevant.

The Larger Lesson

Deadlines under tax laws are important because they bring certainty and finality to proceedings.

But the law also recognises that every case does not arise in identical circumstances.

The Bhagwati Industries decision serves as a reminder that, in exceptional cases, the story behind the delay may matter alongside the delay itself.

For businesses facing an old GST dispute, the practical message is simple:

Before concluding that a matter is “too late”, examine the facts, the reason for the delay and the legal jurisdiction that may still be available.

Case Citation

Bhagwati Industries v. Union of India & Ors.
2026 (7) TMI 1835
High Court of Judicature for Rajasthan (Bench at Jaipur)
D.B. Civil Writ Petition No. 11651/2026
URN: CW / 25776U / 2026

Can a GST Appellate Authority Remand a Case? Understanding the Limits of Section 107(11)

An appeal is intended to provide a taxpayer with an opportunity to challenge an order passed during adjudication. But what happens when the Appellate Authority, instead of deciding the appeal, sends the matter back to the original authority for fresh consideration?

Can the Appellate Authority simply remand the matter?

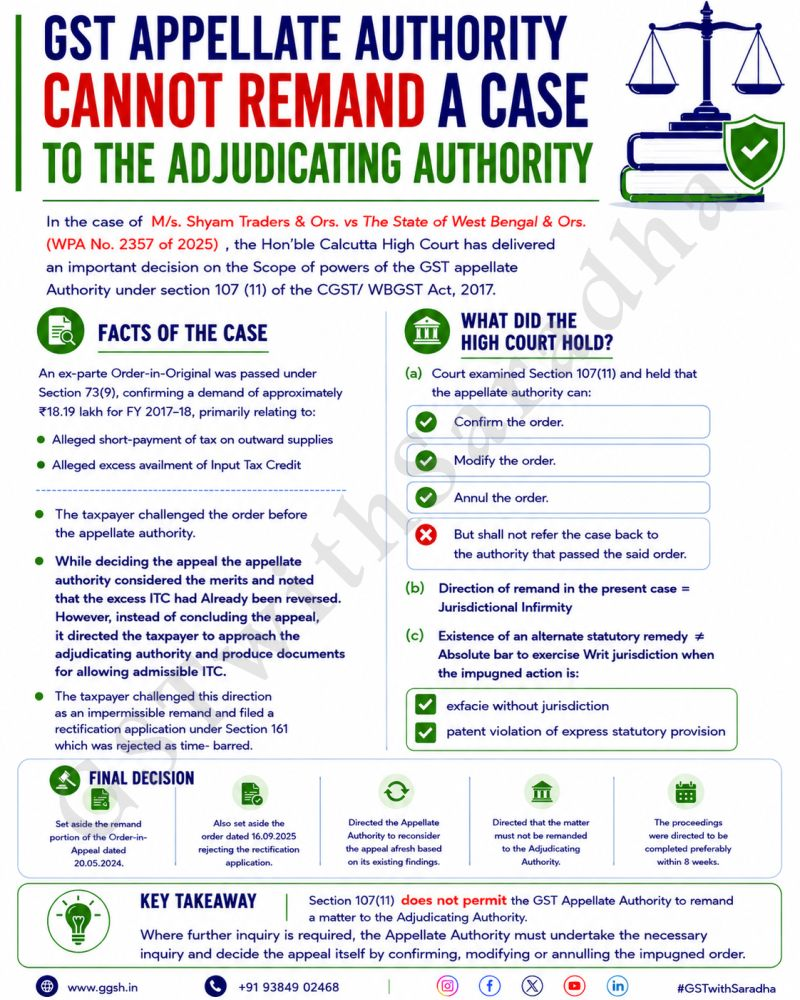
The Calcutta High Court recently examined this question in M/s. Shyam Traders & Ors. v. State of West Bengal & Ors.

What Does Section 107(11) Provide?

Section 107(11) of the GST law sets out the powers available to the Appellate Authority while deciding an appeal.

The Appellate Authority may, after making further inquiry where necessary:

  • Confirm the order;
  • Modify the order; or
  • Annul the order.

The question before the Court was whether these powers also include an independent power to remand the matter back to the original adjudicating authority.

The Court’s View on Remand

The Calcutta High Court held that remand is not one of the powers expressly provided to the Appellate Authority under Section 107(11).

While the provision permits the Appellate Authority to conduct further inquiry where necessary, the Court distinguished such inquiry from sending the entire matter back to the original authority for a fresh decision.

In other words, the power to make further inquiry does not automatically translate into a power to remand.

The statutory powers have to be exercised within the boundaries specifically provided by the legislation.

Why Does This Matter to Taxpayers?

At first glance, remanding a matter may appear to be a procedural step.

For a taxpayer, however, it can have significant practical consequences.

A remand may result in:

  • Another round of adjudication;
  • Fresh submissions and hearings;
  • Additional documentation and explanations;
  • Further proceedings before the original authority; and
  • Prolonged resolution of the dispute.

An appellate remedy is intended to provide an effective mechanism for challenging an order. Therefore, the scope of the Appellate Authority’s statutory powers becomes particularly important.

Further Inquiry Is Not the Same as Remand

One of the important distinctions emerging from the decision is between conducting further inquiry and remanding the proceedings.

Section 107(11) permits the Appellate Authority to make further inquiry where necessary before arriving at its decision.

However, according to the Court, this does not mean that the Appellate Authority can routinely return the matter to the adjudicating authority and require the entire process to begin again.

The appellate authority must operate within the powers granted to it by the statute.

What Did the High Court Do?

The Calcutta High Court set aside the remand order and directed the Appellate Authority to reconsider the appeal in accordance with law, based on the findings and material available before it.

The decision therefore reinforces the principle that statutory authorities cannot exercise powers beyond the authority conferred upon them by the legislation.

The Broader Legal Principle

The significance of this decision goes beyond the question of remand.

In tax litigation, it is common to focus heavily on the merits of the demand—whether tax is payable, whether ITC is admissible, whether a particular transaction is genuine, or whether a procedural requirement has been satisfied.

But there is another equally important question:

Does the authority actually have the statutory power to take the action it has taken?

An order may therefore be challenged not only on the merits of the tax dispute but also on the ground that the authority has acted beyond its prescribed jurisdiction or statutory powers.

Practical Takeaway for Taxpayers

When an adverse GST appellate order is received, taxpayers should examine more than just the final tax demand.

It is important to consider:

1. What powers does the authority have under the relevant provision?

2. Was the authority acting within those statutory powers?

3. Was the matter properly decided, or was it unnecessarily sent back for another round of proceedings?

4. Does the appellate order comply with the procedure prescribed under the GST law?

Understanding these questions can be particularly important in litigation because jurisdiction and statutory authority can be as significant as the underlying tax issue.

Conclusion

The Shyam Traders decision highlights a fundamental principle of administrative and tax law:

An authority can exercise only those powers that the law has conferred upon it.

Section 107(11) gives the Appellate Authority specific powers to confirm, modify or annul an order, while permitting further inquiry where necessary.

According to the Calcutta High Court, those powers do not include a general power to remand the matter to the original authority.

For taxpayers, the lesson is clear:

In an appeal, don’t look only at the tax demand. Look at the power behind the order.

Understanding the boundaries of statutory authority can sometimes be just as important as contesting the tax liability itself.

Case Citation

M/s. Shyam Traders & Ors. v. State of West Bengal & Ors.
WPA No. 2357 of 2025
Calcutta High Court
Decided on: 9 July 2026

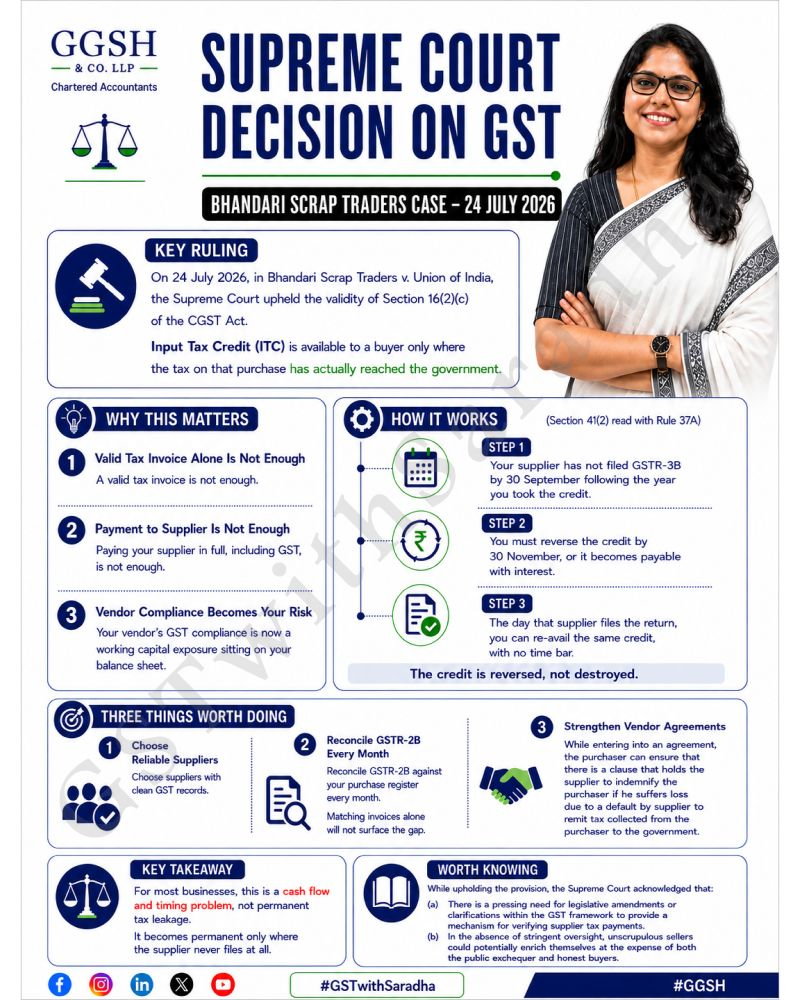
ITC and Supplier Default: What the Bhandari Scrap Traders Decision Means for Businesses

The Supreme Court’s dismissal of the SLP in Bhandari Scrap Traders v. Union of India & Ors. has brought significant attention to the operation of Section 16(2)(c) of the CGST Act and the impact of supplier tax compliance on the recipient’s Input Tax Credit (ITC).

At its core, the issue is straightforward:

Can a recipient claim ITC when the supplier has not actually discharged the tax payable to the Government?

The decision, however, goes beyond simply answering this question.

The Background: Section 16(2)(c)

Section 16(2)(c) of the CGST Act makes payment of the tax charged on the supply to the Government, either in cash or through utilisation of ITC, one of the conditions for claiming ITC.

This creates an important practical issue for genuine purchasers.

A recipient may have:

  • A valid tax invoice;
  • Paid the supplier;
  • Actually received the goods or services; and
  • Complied with other applicable requirements.

Yet, if the supplier fails to discharge the corresponding tax liability, the recipient’s ITC position may still be affected.

This was the central concern examined by the Gujarat High Court.

The Quest Merchandising Argument

One of the important arguments considered by the Gujarat High Court was whether the reasoning adopted by the Delhi High Court in Quest Merchandising could be applied to the GST regime.

In Quest Merchandising, the Delhi High Court had examined the relevant provisions under the erstwhile DVAT regime and considered the difficulties faced by genuine purchasers in independently verifying whether the supplier had actually discharged its tax liability.

A similar line of reasoning was subsequently considered by the Tripura High Court in Sahil Enterprises in the context of Section 16(2)(c) of the CGST Act.

The underlying concern was simple:

How can a genuine purchaser ensure compliance with a condition that substantially depends upon the conduct of the supplier?

Why the Gujarat High Court Took a Different View

The Gujarat High Court did not accept that the reasoning in Quest Merchandising could simply be transplanted into the GST framework.

The Court examined the GST legislation as a complete and interconnected statutory framework.

In particular, it considered the relationship between:

  • Section 16(2)(c);
  • Section 41(2); and
  • Rule 37A.

These provisions contemplate mechanisms for dealing with situations where the supplier has not discharged the tax liability, including reversal of ITC and subsequent re-availment when the relevant tax is ultimately paid.

Therefore, according to the Court, Section 16(2)(c) cannot be examined in isolation from the wider GST mechanism.

The Destination-Based Nature of GST

The Court also considered the fundamental nature of GST as a destination-based consumption tax.

The GST framework, including the IGST mechanism, involves the movement and settlement of tax revenues between jurisdictions based on the place of supply.

Allowing ITC merely on the strength of an invoice, without the corresponding tax actually reaching the Government, could have implications for the revenue of the State in which the supply is ultimately consumed.

This was an important factor in understanding why the statutory condition under Section 16(2)(c) could not simply be disregarded.

Can the Provision Be “Read Down”?

Another significant issue was the doctrine of reading down.

The argument in such cases is generally that a statutory provision should be interpreted narrowly when its literal operation creates an unfair or constitutionally problematic consequence.

However, the Gujarat High Court emphasised that reading down is not a tool that can be used merely because a statutory provision creates hardship or inconvenience.

It becomes relevant where giving the provision its plain meaning would result in a genuine constitutional infirmity.

According to the Court, the GST framework already contains mechanisms to address supplier default and provide for corrective action.

Therefore, the existence of difficulties faced by genuine purchasers was not, by itself, sufficient to invalidate or read down Section 16(2)(c).

ITC Is a Statutory Benefit

The judgment also reiterates an important principle in indirect taxation:

ITC is not an unconditional or vested right.

It is a statutory benefit available subject to fulfilment of the conditions prescribed by the legislation.

Consequently, equitable considerations or the fact that a purchaser acted in good faith cannot, by themselves, override an express statutory condition.

This does not mean that the difficulties faced by genuine taxpayers are insignificant.

In fact, the Court acknowledged those concerns.

But the solution, in the Court’s view, lies in strengthening the GST system and its administrative mechanisms rather than rewriting the statutory condition through judicial interpretation.

The Court’s Concern for Genuine Purchasers

Importantly, the judgment did recognise the practical difficulties that bona fide purchasers may face when their ITC is affected because of supplier default.

The Court urged the Government to consider mechanisms such as:

  • Real-time verification of supplier tax payments;
  • Stronger recovery mechanisms against defaulting suppliers; and
  • Measures that reduce the disproportionate burden placed on genuine purchasers.

This is significant because the Court recognised the gap between the legal condition for ITC and the practical ability of a recipient to monitor a supplier’s tax compliance.

What Does This Mean for Businesses?

The decision reinforces an important practical reality:

Your supplier’s GST compliance can directly affect your ITC position.

A business should therefore not stop its due diligence at merely collecting an invoice.

The following become increasingly important:

1. Verify Supplier Details

Ensure that suppliers are properly registered and their GST details are consistent with the transaction.

2. Reconcile GSTR-2B Regularly

Regular reconciliation can help identify mismatches and potential supplier-side compliance issues at an early stage.

3. Monitor Vendor Compliance

For significant vendors, businesses should consider periodic monitoring of return filing and GST compliance.

4. Maintain Complete Transaction Evidence

Invoices, purchase orders, payment records, delivery documents and proof of receipt of goods or services should be maintained systematically.

5. Consider Contractual Safeguards

Commercial agreements with suppliers can include appropriate GST compliance obligations and mechanisms for addressing tax or ITC-related consequences arising from supplier default.

The Larger Lesson

The Bhandari Scrap Traders decision highlights an uncomfortable but important reality of the GST system.

A transaction may be genuine.

The purchaser may have paid the supplier.

The goods or services may have actually been received.

Yet the recipient’s ITC position can still be affected by the supplier’s failure to discharge the corresponding tax liability.

Therefore, supplier due diligence is no longer merely a procurement or accounting function. It can directly become an ITC risk-management function.

For businesses, the message is clear:

A valid invoice is important. Payment is important. Receipt of goods or services is important. But supplier compliance can complete – or affect – the ITC story.

The transaction may be between you and your supplier.

But under the GST framework, the ITC exposure can travel with your supplier too.

Case Reference

Bhandari Scrap Traders v. Union of India & Ors.

The Supreme Court’s dismissal of the SLP has left the Gujarat High Court’s reasoning concerning Section 16(2)(c) of the CGST Act undisturbed.

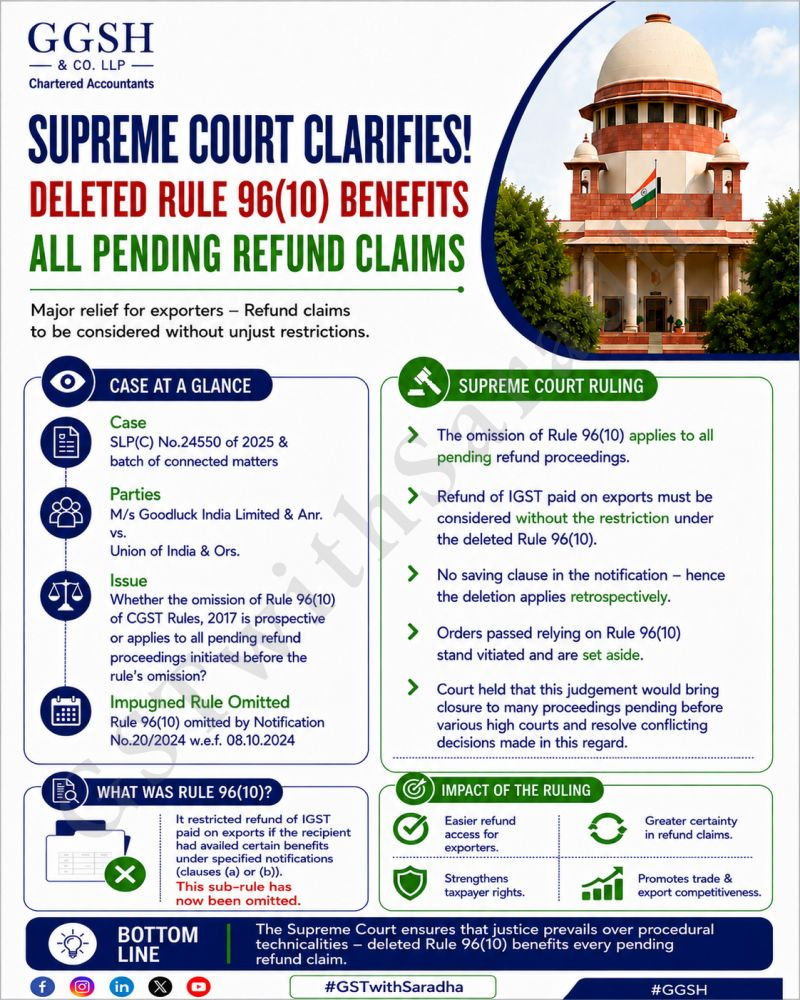
Rule 96(10) Omitted: What Does the Supreme Court’s Goodluck India Decision Mean for Pending IGST Refunds?

For exporters, disputes relating to Rule 96(10) of the CGST Rules have remained a significant source of uncertainty, particularly where IGST refunds were withheld or rejected on the ground of alleged non-compliance with the provision.

The Supreme Court’s recent decision in M/s Goodluck India Limited & Anr. v. Union of India & Ors. provides important clarity on the legal consequences of the subsequent omission of Rule 96(10).

The Background: Rule 96(10) and IGST Refunds

Rule 96(10) had placed restrictions on the availability of refund of IGST paid on exports in specified circumstances, particularly where the exporter had availed certain specified benefits relating to procurement or input taxes.

Over time, disputes arose regarding the validity, applicability and continuing effect of the provision.

A particularly important question was:

What happens to proceedings that were still pending when Rule 96(10) was omitted?

This question became significant for exporters whose refund claims, adjudications, appeals or writ proceedings continued even after the provision ceased to exist.

The Omission of Rule 96(10)

Rule 96(10) was omitted with effect from 8 October 2024.

The significance of the amendment was not limited to future transactions.

The question was whether the omitted provision could continue to be relied upon by the Department in proceedings that were still pending as on the date of omission.

In Goodluck India Limited, the Supreme Court considered this issue in the context of pending proceedings concerning IGST refunds.

The Supreme Court’s Decision

In M/s Goodluck India Limited & Anr. v. Union of India & Ors., SLP(C) No. 24550/2025 and connected matters, the Supreme Court dismissed the appeals filed by the Union of India on 6 August 2026.

The decision upheld the view that the omission of Rule 96(10), effective from 8 October 2024, has consequences for proceedings that remained pending on that date.

A significant aspect of the reasoning concerns the legal effect of omitting a statutory provision without a saving clause.

Why the Absence of a Saving Clause Matters

When a statutory provision is removed, an important question arises:

Can the omitted provision continue to govern pending proceedings?

The Supreme Court’s approach draws upon the Constitution Bench decision in Kolhapur Canesugar Works Ltd. v. Union of India, which examined the legal consequences of repeal or omission of statutory provisions in the absence of a saving clause.

Where an existing provision is omitted without a saving provision preserving its operation for pending matters, the omitted provision cannot simply continue to be treated as though it remains part of the law.

This principle became particularly relevant to Rule 96(10).

Once the provision was omitted, its continued use as a basis for restricting refund claims in pending matters had to be examined in light of the legal effect of that omission.

What Could This Mean for Pending Refund Matters?

The decision can have practical significance in cases where Rule 96(10) was relied upon as the basis for withholding or rejecting an export refund.

Potentially relevant matters may include:

1. Refunds Withheld or Rejected on Rule 96(10) Grounds

Where a refund was denied specifically because of alleged contravention of Rule 96(10), the order may require fresh examination in light of the Supreme Court’s decision.

2. Pending Adjudication Proceedings

Where the alleged contravention of Rule 96(10) remains the principal or sole basis of the proceedings, the subsequent omission of the provision may have a direct bearing on the matter.

3. Pending Appeals and Writ Proceedings

Cases that were pending when Rule 96(10) was omitted may need to be reviewed to determine the impact of the Supreme Court’s ruling.

4. Existing Orders Based on Rule 96(10)

Where an earlier order has relied upon Rule 96(10), taxpayers may need to examine whether consequential relief or further legal action is available in light of the subsequent judicial development.

What the Judgment Does Not Mean

The decision should not be understood as creating an automatic refund entitlement for every exporter who was previously affected by Rule 96(10).

The omission of Rule 96(10) does not remove the other statutory requirements applicable to refund claims.

Exporters must still satisfy the relevant provisions governing refund eligibility and establish compliance with other applicable conditions.

Therefore, the correct approach is not:

“Rule 96(10) is gone, so every refund must now be granted.”

Rather, the question is:

“Was the refund withheld or rejected specifically because of Rule 96(10), and what is the effect of its omission on that pending matter?”

That distinction is important.

What Should Exporters Do Now?

Businesses with old or pending refund disputes should consider reviewing their files systematically.

Step 1: Identify Pending Refund Matters

Prepare a list of refunds that remain:

  • Withheld;
  • Rejected;
  • Under adjudication;
  • Under appeal; or
  • Under writ proceedings.

Step 2: Check Whether Rule 96(10) Was Relied Upon

Review the relevant:

  • Refund rejection orders;
  • Show Cause Notices;
  • Adjudication orders;
  • Appeal orders; and
  • Correspondence with the Department.

Identify whether Rule 96(10) was the sole or principal ground for the adverse action.

Step 3: Review the Export Documentation

Even where Rule 96(10) is no longer available as a ground, other refund requirements continue to matter.

Therefore, exporters should reconcile and verify:

  • Export invoices;
  • Shipping bills;
  • Bills of lading or airway bills;
  • GST returns;
  • Payment realisation records;
  • Relevant refund applications; and
  • Other supporting documents.

Step 4: Examine Consequential Relief

Where an existing order was based on Rule 96(10), the taxpayer should examine the appropriate legal mechanism for seeking consequential relief in light of the Supreme Court’s ruling.

The Larger Lesson

The Goodluck India decision demonstrates that an amendment or omission to tax legislation can have consequences that extend beyond the date on which the change comes into force.

For businesses, the legal effect of an amendment must therefore be examined not only prospectively but also in relation to pending proceedings and existing disputes.

For exporters who have been waiting for years for their IGST refunds, this may be an important opportunity to revisit matters that were previously considered blocked by Rule 96(10).

The practical message is simple:

If Rule 96(10) was the reason your refund was withheld, rejected or disputed, the matter may deserve a fresh review in light of the Supreme Court’s decision.

The omission of a provision can sometimes change not only what businesses must do going forward, but also how yesterday’s pending disputes need to be viewed today.

Case Reference

M/s Goodluck India Limited & Anr. v. Union of India & Ors.
SLP(C) No. 24550/2025 & connected matters
Supreme Court of India
Decision: 6 August 2026

Relevant precedent: Kolhapur Canesugar Works Ltd. v. Union of India