

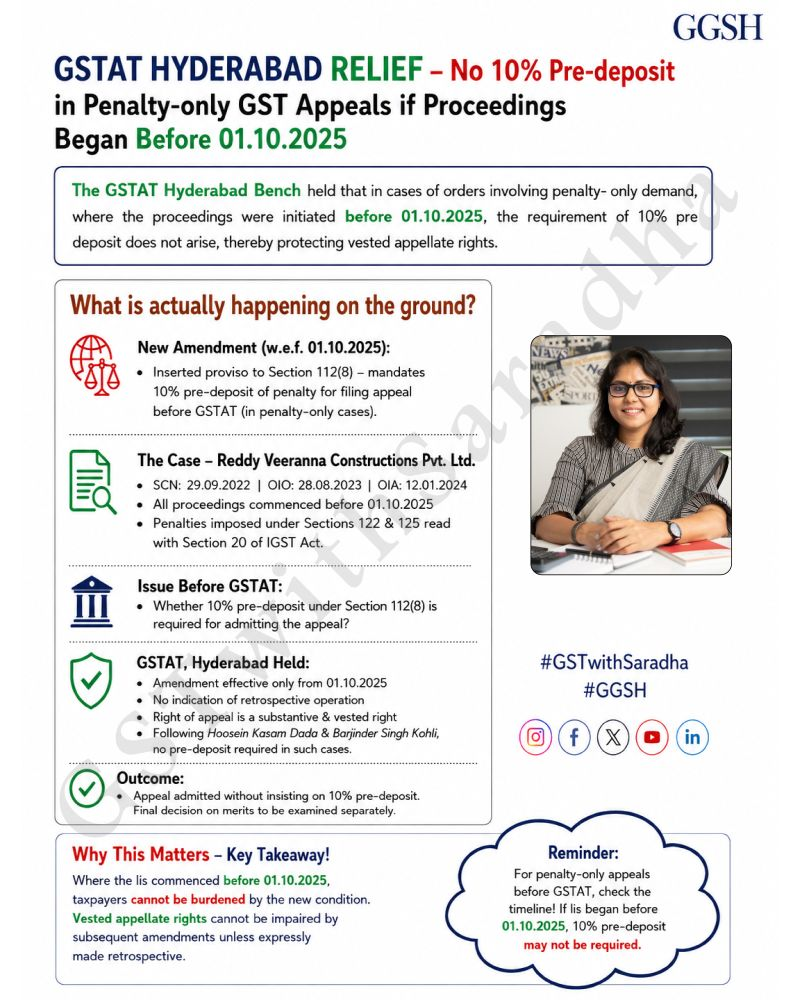
A statutory amendment may change the procedure for future appeals. But can it impose a new condition on an appellate right that had already accrued?
This question recently came before the GSTAT, Hyderabad Bench in Reddy Veeranna Constructions Pvt. Ltd. v. Appeal-I Commissioner & Ors., APL/623/HYD/2026.
The issue was whether the newly introduced requirement of a 10% pre-deposit for penalty-only appeals, under the proviso to Section 112(8) of the CGST Act, could be insisted upon where the underlying proceedings had commenced before 1 October 2025.
The Tribunal answered in the negative.
The Core Legal Issue
The requirement of a 10% pre-deposit was introduced with effect from 1 October 2025.
The question, therefore, was not simply when the appeal was filed. The more fundamental issue was whether a subsequent statutory condition could be applied to an appellate right arising from proceedings that had already commenced before the amendment.
The Tribunal relied on the well-established principle that a right of appeal is a substantive and vested right.
Unless the legislature clearly provides for retrospective application, a subsequent amendment imposing an additional condition on that right cannot ordinarily be applied retrospectively.
Reliance on Established Judicial Principles
In reaching its conclusion, the Tribunal relied upon the principles laid down by the Hon’ble Supreme Court in Hoosein Kasam Dada (India) Ltd. v. State of Madhya Pradesh and the Calcutta High Court in Barjinder Singh Kohli.
The underlying principle is significant:
A vested right of appeal cannot ordinarily be burdened with a new statutory condition unless the law clearly indicates that such condition is intended to operate retrospectively.
Applying this principle, the GSTAT held that no 10% pre-deposit was required for penalty-only appeals where the lis had commenced before 1 October 2025.
Why Does This Matter?
The significance of the order goes beyond the particular taxpayer involved.
Tax laws frequently undergo procedural and statutory changes. When a new condition is introduced, the critical question is not merely:
“When did the amendment come into force?”
It is also:
“When did the right or proceeding to which the amendment is sought to be applied arise?”
This distinction can become particularly important where a new condition increases the financial or procedural burden on an existing appellate right.
Important Limitation
The Tribunal’s order was confined to the issue of admission and pre-deposit.
It did not decide the appeal on merits.
Therefore, the order should not be understood as determining whether the penalty itself was sustainable. Its significance lies specifically in determining whether the newly introduced pre-deposit requirement could be imposed in the circumstances of the case.
Practical Takeaway for Taxpayers
Taxpayers facing penalty-only appeals arising from proceedings initiated before 1 October 2025 should carefully examine:
- The date on which the underlying proceedings commenced;
- The statutory provision under which the penalty was imposed;
- The date and nature of the appellate right;
- The amendment introducing the 10% pre-deposit requirement; and
- Whether the amendment contains any express provision giving it retrospective effect.
A change in law does not automatically mean that every existing proceeding becomes subject to the new condition.
The Larger Principle
The decision reinforces an important principle of appellate jurisprudence:
A vested right of appeal cannot ordinarily be burdened by a subsequent statutory condition unless the legislature clearly intends such retrospective application.
For taxpayers, therefore, the timeline of the proceedings can be just as important as the amendment itself.
Case: Reddy Veeranna Constructions Pvt. Ltd. v. Appeal-I Commissioner & Ors.
GSTAT, Hyderabad Bench
APL/623/HYD/2026
Key takeaway:
New appellate conditions do not automatically apply to every proceeding that was already in motion. The date on which the lis commenced may make a critical difference.
