URP Purchases under GST: Simple on Paper, Risky in Practice ⚠️

Purchasing from Unregistered Persons (URPs) often looks like routine procurement…

But in reality?
It quietly brings in compliance exposure that many businesses underestimate.

Especially when:

  • Volumes increase 📈
  • Transactions become frequent 🔁
  • Or audits begin 🔍

⚠️ Where the Risk Actually Lies

URP transactions can trigger:

  • Reverse Charge Mechanism (RCM) liability
  • E-way bill responsibility shifting to the recipient
  • Documentation gaps (no GST invoice from supplier)
  • Reporting mismatches in returns

👉 What starts as a simple purchase can quickly turn into a compliance blind spot

📋 URP Procurement & GST Compliance Checklist

To address this, we’ve built a practical, workflow-driven checklist covering:

🧾 Vendor Due Diligence

  • KYV (Know Your Vendor)
  • PAN validation
  • GST registration status check

🌍 Transaction Structuring

  • Inter-State vs Intra-State classification
  • Place of supply determination

🚚 Logistics & Movement

  • E-way bill responsibility when supplier is unregistered
  • Ensuring transporter-level compliance

🧮 RCM Compliance

  • Self-invoice generation timelines
  • Payment voucher requirements
  • Tax payment under RCM

📊 Return Reporting

  • Accurate disclosure in:
    • GSTR-3B
    • GSTR-9
    • GSTR-9C

📁 Documentation & Audit Readiness

  • Record retention
  • Invoice mapping
  • Reconciliation with books

🎯 Why This Matters

This checklist is not about theory.

It is designed to:

✔ Help procurement & finance teams ask the right questions upfront
✔ Avoid downstream disputes and notices
✔ Ensure compliance without slowing business operations

💡 Practical Insight

👉 URP transactions are not risky because they are complex…
👉 They are risky because they are treated as routine

💬 Final Thought

If URP purchases are part of your operating model:

Don’t wait for audit observations to highlight gaps.
Build controls at the transaction stage itself.

📄 We’ve shared a one-page URP Procurement Checklist for easy reference.💬 If you need clarity on RCM, documentation, or return reporting, feel free to reach out—happy to walk you through real scenarios 👍🏼
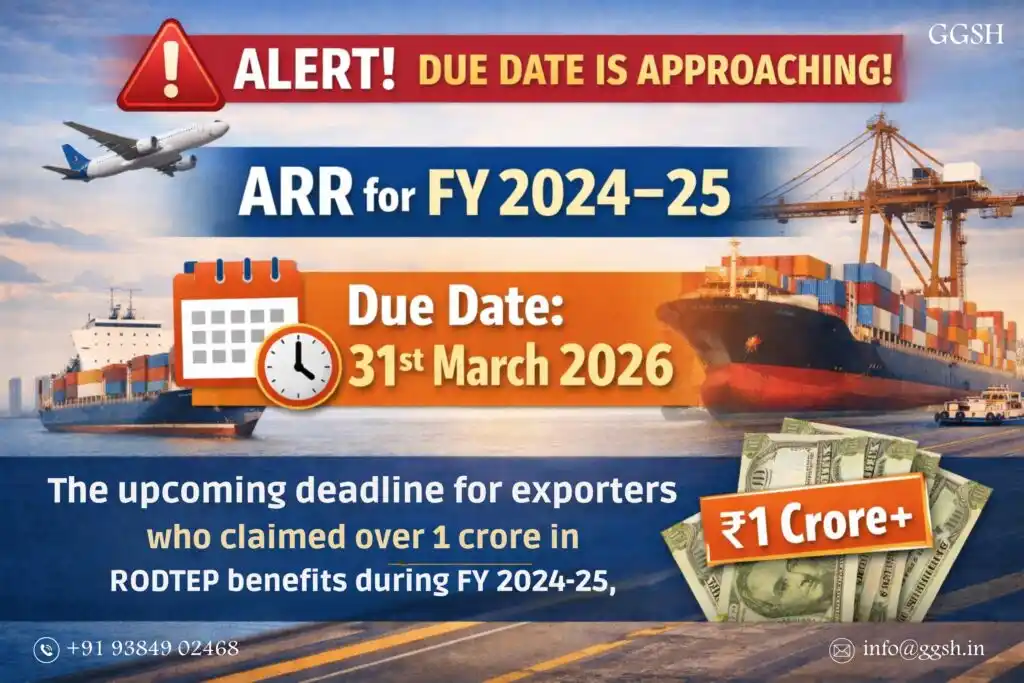
Annual RoDTEP Return- ARR FAQs – Your Ultimate Guide

Exporters of Goods, don’t let your RoDTEP scrips slip through the cracks!

You forget to switch on the motor, until you find air gush through the water tap! But remember it takes time to fill the tank and get the water again.. how do you manage the interim cash flow?

RoDTEP is not just a scrip but a real profit element and important feed to cash flow for every exporter. Exporters have already faced a steep reduction in the rate of scrip benefits over these years; and now its time to secure at least what is left with! It has been more than a month since the actual due date 30th June 2025 has crossed. Yet many exporters ask these questions: What? Is there one such return to be filed?

> We are keeping it pending not knowing how to go about..
> Busy with Financials & Audit closure
> Somebody said I can still file with nominal late fees
> Oh, but I keep getting RoDTEP scrips without any issues as of now

But remember all these are only until 30th September 2025 and then your scrip inflow stops there, if you haven’t filed ARR!

Imagine the amount of efforts your organisation takes to make export and gain that “1 Crore+ of RoDTEP scripts”. Now you can’t afford to lose that simply due to non filing of a return – ARR!

If you’re sending goods out of India, there’s this “not-so-talked-about filing” that needs your attention – the 𝗔𝗻𝗻𝘂𝗮𝗹 𝗥𝗼𝗗𝗧𝗘𝗣 𝗥𝗲𝘁𝘂𝗿𝗻 for FY 2023-24.

Due date extended to 30th June 2025 & Late fee window open till 30th September 2025.

Miss this, and you might end up losing script credits you actually deserve!

And it’s not a straight forward one to file something on the last date…. This one pulls out real business costs – like diesel usage, logistics, electricity bills, factory overheads, and even those tiny embedded taxes most people forget to track.

Plus, it’s not just about filing and forgetting. DGFT will review what you submit. So if numbers don’t match up or seem off, it could cause issues later. So, to help you out, we’ve prepared one-stop-solution: “Annual RoDTEP Return – ARR FAQs – Your Ultimate Guide”

Annual RoDTEP Return

MADE FOR EXPORTERS of GOODS

EXPORT Industry Associations Trade & Commerce Chambers Freight Forwarders & Logisticians Customs & FTP Professionals Tax & Finance Professionals Government & Policy Analysts

1. WHAT is RoDTEP

The Scheme provides a mechanism for re-imbursement of taxes/ duties/ levies, (eg. Electricity Duty/VAT or Excise Duty on fuel etc,.) which are currently not being refunded under any other mechanism, at the central, state and local level, but which are incurred in the process of manufacture and distribution of exported products, to the exporting industries in India. Exporters of eligible items under the Scheme are being issued e-scrips. The e-scrips are transferable and are used for payment of basic customs duty.

2. WHAT is ARR

All the exporters claiming RoDTEP benefit shall file Annual RoDTEP Return (ARR), to assess the nature of inputs used in production for the export and the amount of actual taxes & duties incurred, as permissible under Para 4.54 of FTP (Operational framework of Remission of Duties and taxes on Exported products).

3. For WHOM ARR is applicable

If the total RoDTEP claim for a given IEC exceeds Rs. 1 crore in a financial year, filing the Annual RoDTEP Return (ARR) is mandatory Separate return applications are required to be filed for DTA and for AA/EoU/SEZ Exports.

4. WHY RoDTEP return- What will the Government do with ARR

ARR filings undergo periodic assessment for due diligence and may be reviewed by the RoDTEP Committee for necessary rate revisions, including consideration of higher rates if justified.

Thus, ARR submitted by exporters in every industry becomes the basis for determining the rate of RoDTEP.

5. WHAT is the BENEFIT of filing this ARR for an EXPORTER

i. Promotes transparency by requiring detailed cost, duty, and tax data.
ii. Standardized filing process reduces errors and inconsistencies in claims.
iii.Enhance the exporter’s credibility by aligning with global trade documentation standards
iv. Dynamic scheme allows rate adjustments based on real data,ensuring fair export cost reflection.
v. Ensures only actual duties, taxes, and levies are claimed, preventing inflated claims.

6. WHEN – Is there any time limit to file

ARR for RoDTEP claims filed in a particular financial year shall be filed on DGFT portal by 31st March of the next financial year i.e. RoDTEP claims information for Financial Year 2023-24 shall be required to be filed by 31.03.2025.

However for FY 23-24,  this date was extended to 30.06.2025.

7. What are the CONSEQUENCES of non-filing

Non-reporting of the ARR shall lead to denial of benefits under the RoDTEP scheme and No further scroll out of RoDTEP claims for the SBs will be permitted at the Customs Port of Export after the grace period of three (3) months i.e. after 30th June.

For FY 23-24,  this  grace period is extended to 30 September 2025

8. Whether DELAYED FILING is permissible

A composition fee of Rs. 10,000/- will need to be paid for delayed filing of each ARR up to 30th sep 2025. thereafter a composition fees of Rs. 20,000/- will need to be paid for filing of each ARR after 30th sep 2025.

Subsequent to the payment of the applicable composition fee, the RoDTEP scrolls will be resumed within 45 days, till an online API based message exchange is established between DGFT and Customs.

The resumption of scroll out shall also cover the Shipping Bills that were not scrolled out earlier on account of non-compliance of ARR.

9. HOW to REPORT – HSN code wise 

The exporter must file an ARR for the ITC-HS code with the highest claim. If any individual ITC-HS code surpasses Rs. 50 lakhs, an ARR must be filed for each of those codes.

Refer below table for clear understanding –

S.noScenarioRODTEP Claim DistributionARR Filing Requirement
1Case 1 : Highest Claim Rule (Total claim > Rs.1 crore)ITC – HSI : Rs. 15 lakh ITC – HS2 : Rs. 20 lakh ITC – HS3 : Rs. 40 lakh ITC – HS4 : Rs. 30 lakhARR required only for ITC- HS3 (highest claim)
2Case 2 : 50 Lakh Threshhold Rule (Total claim > Rs.1 Highest Claim > Rs.1 crore and any code > Rs.50 lakhs)ITC – HSI : Rs. 60 lakh ITC – HS2 : Rs. 51 lakh ITC – HS3 : Rs. 10 lakh ITC – HS4 : Rs. 20 lakhSeparate ARR required for ITC-HS1 and ITC -HS2 (both exceed Rs.50 lakh)

10. What DATA is primarily required to file the ARR

i. VAT & Excise paid on:

A. Fuel for transportation
B. Fuel for Power generation.

ii. Electricity Duty paid for export product manufacturing

iii. Stamp Duty on relevant export documents.

iv. GST paid under RCM for purchases from unregistered persons.

v. Taxes/duties on raw materials & inputs used in export product manufacturing.

11. Caution – NEED for ACCURACY

A. Record Maintenance: Data must be retained for five years and may be reviewed for ARR assessment, with some cases undergoing IT-based scrutiny (Para 4.54 of FTP).

B. Over-Reporting Risks:Excess RoDTEP claims require refund or surrender; non-compliance may lead to benefit suspension.

C. Under-Reporting Risks:May result in lower RoDTEP rates, affecting the entire industry, as the committee reviews data for necessary rate revisions.

D. Ensuring Seamless Benefits: Accurate reporting is essential for maintaining fair and justified RoDTEP benefits.

12. POINTERS on reporting data

> Tax/Duties/Levies need to be provided in the fields on pro-rata basis.

Wherever approximation is used for calculation, the same should be justified and substantiated at the time of scrutiny in case the return is picked up for scrutiny on the Risk Management System.

The return should be complete to the extent possible. Minor items with low value may be omitted if they don’t significantly alter the amount of remission claimed. The details of the taxes/levies should be limited to those not currently being rebated/refunded through any other mechanism such as GST refunds or exemptions by state/central government.

13. ACTION points Need to ACT NOW

>Gather Essential Data: Track exported goods, VAT & Excise on fuel, and manufacturing inputs, gather the data required from most accurate source.
>Benchmark with Industry Peers: Compare reporting with peers to identify probable discrepancies and minimize inaccuracy.
> Engage with Industry Associations: Collaborate on best practices and uniform approaches.
> Consult Tax Professional: Considering the unique requirement, direct consequences and accuracy required, it would be ideal to seek professional assistance in finalizing and filing, since

14. ARR should be filed online accessible via the DGFT Portal (www.dgft.gov.in) under the Regulations > RoDTEP’ section.

Union Budget 2026: Customs & Excise Reforms Driving Trade, Manufacturing, and Export Growth

The Union Budget 2026 introduces significant reforms in Customs and Excise policy, signalling a strategic shift toward simplified duty structures, export competitiveness, and stronger domestic manufacturing ecosystems.

These changes aim to modernise India’s trade framework by reducing procedural complexity, integrating digital systems, and supporting the government’s long-term Make-in-India and global supply chain ambitions.

The policy direction reflects the broader economic strategy of the Ministry of Finance under the Government of India.

Policy Direction: Simplifying Customs Duty Structures

One of the most important objectives of the Union Budget 2026 customs reforms is the simplification of duty structures.

Historically, India’s customs framework has included multiple exemptions, layered notifications, and complex classification rules, often leading to interpretational disputes and compliance challenges.

The latest reforms aim to:

  • Streamline customs duty structures
  • Reduce dependence on legacy exemptions
  • Embed effective duty rates directly in notifications
  • Improve clarity for importers and exporters

This structural shift is expected to minimise classification disputes and enhance predictability in cross-border trade compliance.

Structural Shift: Phasing Out Legacy Exemptions

Another important change is the gradual phasing out of outdated customs exemptions that have accumulated over time.

Instead of relying on multiple exemption notifications, the government plans to incorporate effective duty rates directly into customs tariff notifications.

This approach offers several benefits:

  • Simplified tariff interpretation
  • Reduced litigation in customs classification disputes
  • Easier compliance for businesses
  • Greater transparency in import duty structures

By simplifying tariff schedules, authorities aim to create a cleaner and more predictable customs framework.

Compliance Simplification: Fewer Classifications, Clearer Rates

The reforms also aim to simplify customs classification and duty rate determination.

Businesses often face challenges due to:

  • Multiple tariff classifications
  • Differing exemption interpretations
  • Complex duty calculations

The updated framework seeks to reduce these complexities by introducing clearer duty structures and fewer interpretational ambiguities.

These improvements are administered through India’s customs authority, the Central Board of Indirect Taxes and Customs.

Export Enablement: Supporting Export-Oriented Industries

A key highlight of the Union Budget 2026 customs reforms is the focus on strengthening India’s export ecosystem.

Several initiatives are designed to support export-oriented industries and improve supply chain efficiency.

Higher Duty-Free Input Limits for Marine Exports

Exporters in the marine products sector will benefit from higher duty-free input allowances, improving competitiveness in international markets.

Extended Export Timelines

The government has also extended export timelines for leather, textile, and footwear sectors, providing additional flexibility for manufacturers to meet global demand cycles.

SEZ–DTA Integration

Another important development is the integration between Special Economic Zones (SEZs) and the Domestic Tariff Area (DTA).

Improved coordination between these zones will help:

  • Optimise asset utilisation
  • Improve production efficiency
  • Strengthen export supply chains

These changes aim to make India’s export ecosystem more flexible and competitive globally.

Make-in-India Push: Strengthening Strategic Industries

The budget also reinforces the Make-in-India strategy by providing duty support for critical sectors.

Key industries receiving customs duty relief include:

  • Clean energy technologies
  • Critical minerals and strategic resources
  • Electronics manufacturing
  • Aerospace and defence supply chains

The reforms also provide long-term policy certainty for nuclear and renewable energy supply chains, encouraging private sector investment and technological development.

These measures aim to strengthen domestic manufacturing capacity and reduce import dependency in strategic sectors.

Trust and Technology: Modernising Customs Administration

Another major transformation in customs governance is the increasing reliance on digital systems and risk-based monitoring.

AEO Programme Enhancements

The Authorised Economic Operator (AEO) programme will see further relaxations, offering trusted businesses simplified customs procedures and faster clearances.

Longer Advance Ruling Validity

Businesses seeking advance rulings on customs classification or valuation will benefit from extended validity periods, improving regulatory certainty.

Digital Trade Infrastructure

Technology-driven reforms include:

  • Single digital window for trade documentation
  • AI-powered cargo scanning systems
  • Fully paperless customs clearances

These initiatives aim to reduce clearance times at ports and improve border efficiency.

Impact on Individuals: Personal Imports and Healthcare

The reforms also bring benefits to individuals and consumers.

Reduced Duty on Personal Imports

Certain personal imports may now attract lower customs duties, making cross-border purchases more affordable.

Expanded Exemptions for Critical Drugs

The budget also expands customs duty exemptions for life-saving drugs and treatments for rare diseases, improving access to critical healthcare products.

These measures highlight the government’s intent to balance trade efficiency with social welfare considerations.

Why These Customs Reforms Matter for Businesses

For importers, exporters, and manufacturers, the Union Budget 2026 customs reforms introduce several advantages:

  • Reduced compliance complexity
  • Faster border clearances
  • Improved tariff clarity
  • Better export incentives
  • Greater investment certainty in manufacturing

Businesses engaged in international trade, supply chain management, and manufacturing will benefit significantly from these reforms.

Bottom Line

The Union Budget 2026 customs and excise reforms mark an important transition in India’s trade policy framework.

Customs administration is gradually moving:

From control-based regulation → to catalyst-driven trade facilitation.With simpler duty structures, digital governance systems, and stronger support for exports and domestic manufacturing, India’s customs ecosystem is evolving toward faster borders, cleaner rules, and stronger global competitiveness.

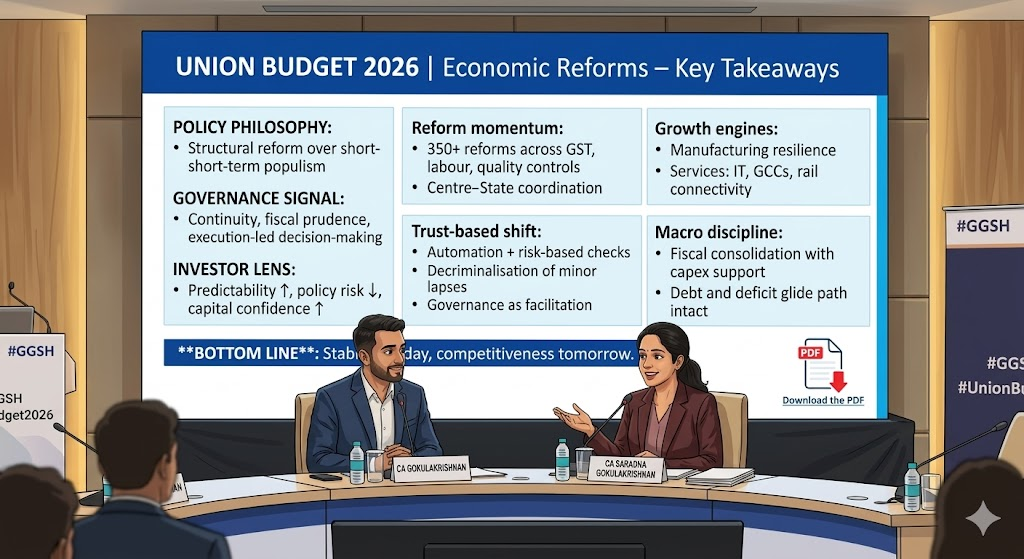
Union Budget 2026 Economic Reforms: Structural Policy Shift Driving India’s Growth

The Union Budget 2026 signals a decisive continuation of structural economic reforms in India, prioritising long-term competitiveness over short-term populism. Rather than focusing on headline announcements, the government has emphasised policy stability, fiscal discipline, and execution-led governance.

For investors, businesses, and policymakers, the message is clear: predictable policy frameworks and systemic reforms will shape India’s economic trajectory in the coming decade.

Policy Philosophy: Structural Reform Over Short-Term Populism

A central theme of Union Budget 2026 economic reforms is the commitment to deep structural transformation rather than temporary stimulus measures.

The policy direction aligns with the broader economic strategy of the Government of India and is implemented through the Ministry of Finance.

This philosophy focuses on:

  • Strengthening institutional frameworks
  • Enhancing regulatory clarity
  • Promoting sustainable economic growth
  • Ensuring long-term macroeconomic stability

Such an approach is designed to build investor confidence while improving the overall business environment in India.

Governance Signal: Continuity and Fiscal Prudence

The budget reinforces the government’s commitment to policy continuity and fiscal prudence.

In recent years, India’s economic policy has increasingly moved toward execution-driven governance, where reforms are implemented gradually but consistently.

Key governance priorities include:

  • Maintaining a disciplined fiscal framework
  • Strengthening institutional capacity
  • Ensuring predictable regulatory environments
  • Improving efficiency in policy implementation

For global investors and domestic businesses alike, policy consistency reduces uncertainty and lowers regulatory risk.

Investor Perspective: Predictability and Confidence

One of the most important outcomes of the reform-oriented approach is the increase in investor confidence.

Stable policy frameworks create a favourable environment for:

  • Domestic investment
  • Foreign direct investment (FDI)
  • Long-term infrastructure financing
  • Capital market participation

When investors perceive lower policy risk and higher regulatory predictability, capital flows tend to increase, strengthening the broader economic ecosystem.

Reform Momentum: 350+ Structural Improvements

India’s reform momentum continues with more than 350 policy and regulatory improvements implemented across multiple sectors.

These reforms cover areas such as:

  • Tax administration and GST processes
  • Labour law rationalisation
  • Quality control standards in manufacturing
  • Digital governance systems

Many of these reforms are implemented through cooperation between the central government and state governments, guided by policy coordination bodies such as the GST Council.

This Centre–State collaboration plays a crucial role in ensuring that reform initiatives translate into real economic outcomes.

Shift Toward Trust-Based Governance

Another key feature of the reform strategy is the transition toward trust-based governance models.

Instead of heavy procedural control, the government is adopting technology-driven monitoring systems combined with risk-based compliance checks.

Key elements of this approach include:

  • Increased automation in regulatory systems
  • Risk-based verification mechanisms
  • Decriminalisation of minor procedural lapses
  • Reduced reliance on manual intervention

These measures are designed to shift governance from control-oriented administration to facilitation-oriented regulation.

Growth Engines: Manufacturing and Services

The budget also highlights the importance of strengthening India’s core economic growth engines.

Manufacturing Expansion

India’s manufacturing strategy focuses on:

  • Building resilient supply chains
  • Deepening domestic value chains
  • Improving quality standards
  • Enhancing export competitiveness

Manufacturing growth supports employment generation and strengthens India’s position in global supply networks.

Services Sector Multipliers

Alongside manufacturing, the services sector continues to play a crucial role in economic expansion.

High-growth segments include:

  • Information technology services
  • Global Capability Centres (GCCs)
  • Data and digital infrastructure
  • Rail connectivity and logistics services

Together, these sectors act as multipliers for productivity and economic growth.

Macro Discipline: Fiscal Consolidation with Growth Support

The budget maintains a strong focus on fiscal discipline while supporting economic growth through capital expenditure.

The fiscal strategy aims to:

  • Maintain a stable debt-to-GDP trajectory
  • Follow a clear deficit reduction glide path
  • Continue strategic public infrastructure investment

This balanced approach ensures that economic expansion is supported without compromising fiscal sustainability.

Why These Reforms Matter for Businesses

For businesses operating in India, the economic reforms outlined in Union Budget 2026 bring several important implications:

  • Greater regulatory clarity
  • Improved ease of doing business
  • Stronger digital governance systems
  • Increased investment opportunities

Companies that align with the evolving policy environment, compliance frameworks, and digital systems will be better positioned to benefit from India’s growth trajectory.

Bottom Line

The Union Budget 2026 economic reform strategy is not about short-term announcements but about systemic transformation of the Indian economy.

The focus is clear:

  • Structural reform instead of temporary policy measures
  • Stable governance frameworks
  • Sustainable fiscal management
  • Long-term competitiveness

In essence, the budget reflects reform by design rather than reform by declaration.The outcome is a policy environment aimed at delivering stability today and stronger economic competitiveness tomorrow.

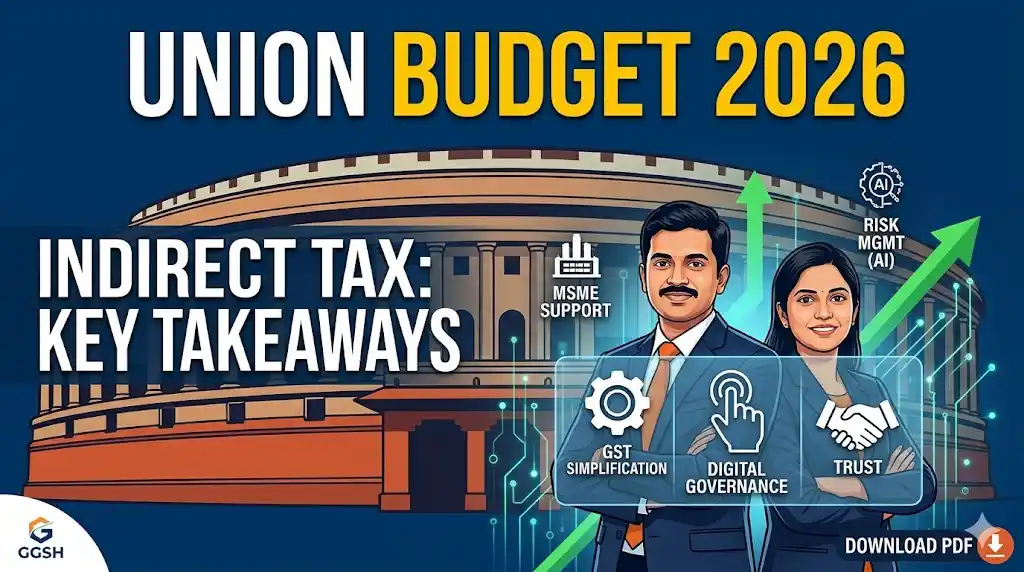
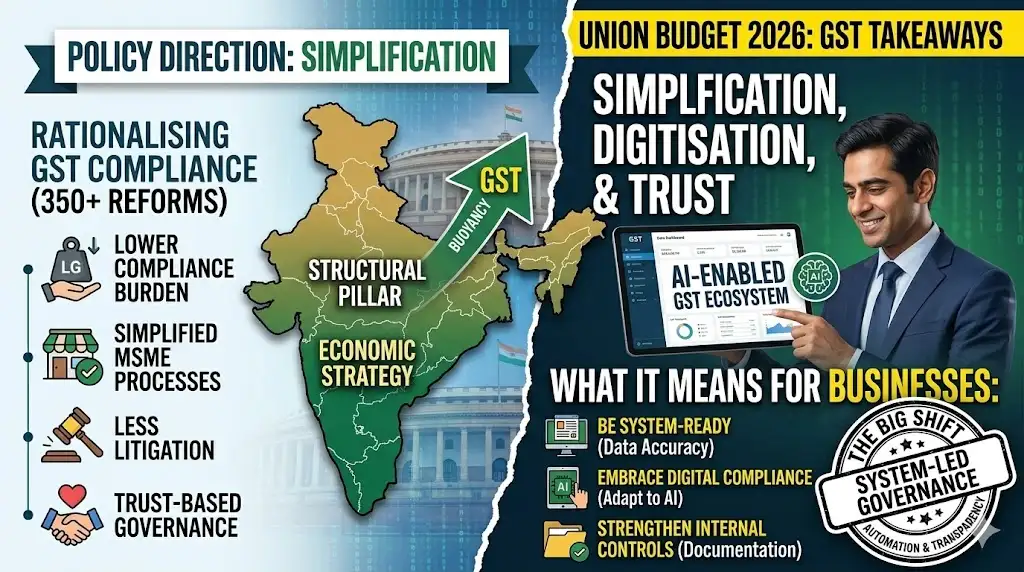
Union Budget 2026: Indirect Tax (GST) – Key Takeaways for Businesses

The Union Budget 2026 signals a continued transformation of India’s indirect tax framework, particularly under the Goods and Services Tax (GST) regime. The focus is clearly shifting toward simplified compliance, technology-driven governance, and trust-based administration.

These developments are expected to further strengthen GST as a core structural reform supporting economic growth, formalisation of businesses, and improved tax efficiency.

Policy Direction: Simplify GST and Digitise Governance

A major theme in the indirect tax announcements is the government’s commitment to simplifying GST compliance while strengthening digital governance.

The GST system, administered through the Goods and Services Tax Network under the policy oversight of the GST Council, continues to evolve toward a technology-first compliance environment.

Key objectives include:

  • Simplifying return filing processes
  • Reducing procedural complexity
  • Increasing transparency in tax administration
  • Strengthening taxpayer trust in the system

This policy direction aims to make GST compliance easier while maintaining robust monitoring mechanisms.

Core Focus: Rationalised GST Compliance

The budget reinforces the need for rationalised GST compliance processes.

Businesses have often faced challenges due to multiple return forms, reconciliations, and procedural checks. The government’s approach now focuses on streamlining these processes to reduce compliance fatigue.

This effort supports the broader goal of improving ease of doing business in India, especially for growing enterprises and new market participants.

Execution Signal: 350+ GST Reforms Already Implemented

Over the past few years, the GST ecosystem has undergone continuous procedural improvements.

According to the policy direction highlighted in the budget, more than 350 reforms and process improvements have already been implemented within the GST framework.

These reforms have included:

  • Simplified return filing processes
  • Faster refund mechanisms
  • Improved invoice matching systems
  • Enhanced taxpayer services

Further process clean-ups and system upgrades are expected in the coming years.

Technology as the Backbone of GST Administration

One of the most important shifts highlighted in the budget is the increasing role of advanced technology in GST governance.

Future GST administration will increasingly rely on AI-enabled analytics and automated systems.

Key technology-driven improvements include:

  • AI-based risk management and fraud detection
  • Automated compliance verification
  • Faster processing of applications and refunds
  • Reduced manual intervention in tax administration

These changes are expected to deliver more predictable outcomes for taxpayers while improving regulatory oversight.

Economic Perspective: GST as a Structural Reform

The budget reaffirms GST as a pillar of India’s economic and fiscal framework.

A well-functioning GST system contributes to:

  • Higher tax buoyancy
  • Improved transparency in business transactions
  • Greater formalisation of the economy
  • Stronger fiscal discipline for governments

By strengthening GST processes, the government aims to support sustainable economic growth while improving revenue stability.

MSME Impact: Reduced Compliance Burden

For Micro, Small, and Medium Enterprises (MSMEs), GST compliance has historically been a major operational challenge.

The reforms highlighted in the budget are expected to:

  • Reduce compliance friction for small businesses
  • Encourage voluntary compliance
  • Lower disputes and litigation
  • Promote trust-based governance between taxpayers and authorities

These improvements can help MSMEs focus more on business growth rather than administrative complexities.

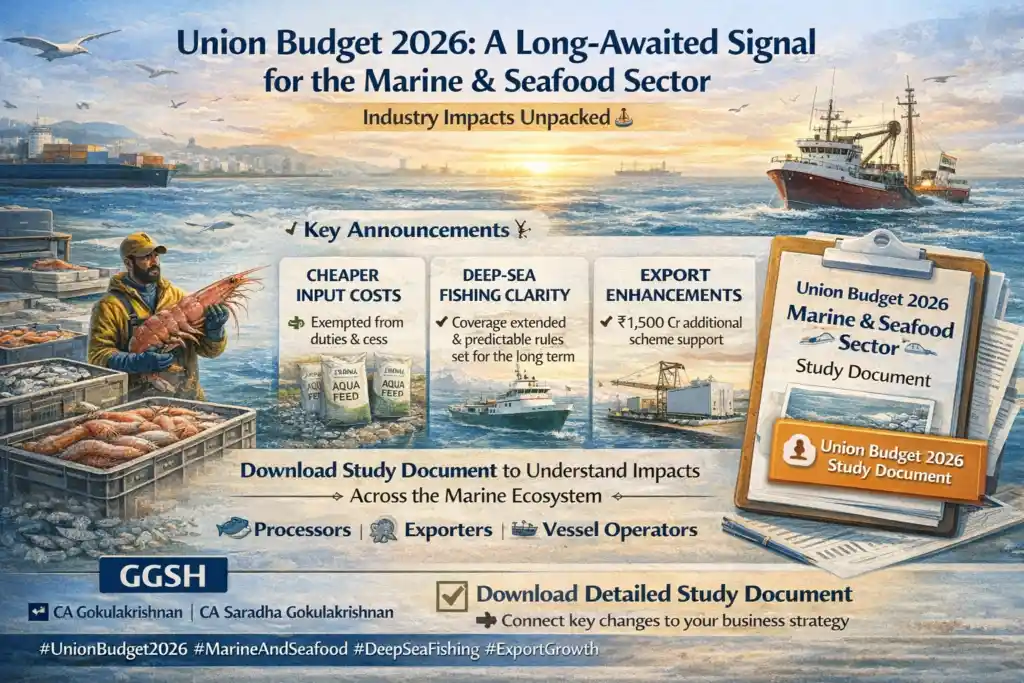
Union Budget 2026: What It Means for India’s Marine & Seafood Export Industry

Budgets are often read for headlines and big announcements.

But industries read them for direction.

For the Marine and Seafood Industry, the Union Budget 2026 feels less like a sudden policy announcement and more like a long-awaited signal that the ecosystem is finally being viewed end-to-end.

For years, businesses across the marine value chain — from deep-sea fishing operators to seafood exporters — have operated in an environment where policy uncertainty, export compliance complexity, and fluctuating input costs created operational challenges.

The 2026 Budget policy direction indicates an effort to address these structural concerns.

And for the seafood sector, clarity often matters more than incentives.

Why Policy Clarity Matters for the Marine Export Ecosystem

The marine and seafood industry functions through a complex value chain involving fishing vessels, processors, cold storage operators, exporters, and logistics providers.

Small policy changes can significantly influence the cost structure and export competitiveness of the sector.

When key variables become predictable:

  • Input costs become easier to manage
  • Export planning becomes more stable
  • Compliance risks reduce
  • Investment decisions become easier

In other words, businesses move from firefighting to forward planning.

Key Budget Signals for the Marine and Seafood Sector

The Union Budget 2026 introduces policy directions that affect multiple parts of the marine ecosystem.

1. Easing of Input Cost Pressures

One of the biggest operational challenges for seafood processors and exporters has been rising input costs — including equipment, fuel, processing infrastructure, and logistics.

Policy adjustments in customs and related frameworks are expected to reduce cost pressures across the marine processing ecosystem.

For exporters, this directly influences international competitiveness in global seafood markets.

2. Greater Policy Clarity for Deep-Sea Fishing Operations

Deep-sea fishing has long required clear regulatory frameworks and predictable compliance guidelines.

The Budget’s approach signals an attempt to bring greater clarity and stability to deep-sea fishing operations, helping vessel operators plan investments in:

  • Fishing vessels
  • Equipment and gear
  • Long-distance fishing operations

For operators managing capital-intensive marine assets, predictability reduces financial risk.

3. Improved Export Policy Predictability

India is one of the world’s major seafood exporters, and policy changes affecting exports can have large downstream implications.

The Budget’s focus on improving export frameworks supports:

  • Simplified export procedures
  • More stable export policy treatment
  • Greater clarity on compliance requirements

This strengthens the operational environment for exporters working with agencies such as the Marine Products Export Development Authority.

Why These Changes Matter for the Marine Value Chain

These policy directions will not transform the industry overnight.

However, they address a challenge that the marine sector has faced for years: persistent regulatory uncertainty.

By reducing ambiguity in key policy areas, the Budget helps improve confidence across the marine value chain.

This benefits stakeholders such as:

Seafood Processors

Processing units rely heavily on stable raw material supply, equipment imports, and export channels.

Policy clarity improves operational planning and production capacity utilisation.

Seafood Exporters

Exporters benefit from predictable compliance frameworks and export procedures, which are critical for maintaining international buyer relationships.

Fishing Vessel Operators

Vessel owners and deep-sea operators require long-term capital planning.

Greater regulatory clarity allows for more confident investment in marine infrastructure.

Clarity vs Incentives: What Drives Sustainable Growth

Government incentives can certainly generate excitement in the short term.

But industries often grow faster when they have something even more powerful: clarity.

  • Incentives create opportunity
  • Policy clarity creates confidence

And confidence is what enables long-term investment, capacity expansion, and export growth.

For the marine and seafood industry, removing uncertainty can unlock more growth than short-term fiscal incentives.

Understanding the Impact Across the Marine Ecosystem

At GGSH, we analysed the policy changes introduced in Union Budget 2026 and studied how they impact different segments of the marine value chain.

Our detailed industry study breaks down the implications for:

  • Seafood processors
  • Marine exporters
  • Fishing vessel operators
  • Deep-sea fishing businesses

The analysis connects policy changes to practical business outcomes, helping stakeholders understand where the real impact lies.

Download the Detailed Marine Industry Budget Analysis

If you are part of the marine and seafood value chain, this study can help you:

  • Understand the policy implications of Union Budget 2026
  • Identify cost and compliance impacts on your business
  • Plan your export and operational strategies more effectively

📥 Download the detailed study document to explore the full analysis.

If you would like to discuss how these changes affect your specific business operations, feel free to reach out to the GGSH team.

Final Thoughts

The Union Budget 2026 may not have introduced dramatic incentives for the marine industry.

But it sends a much stronger signal — the sector is finally being looked at as a complete ecosystem.

And when industries receive clarity, predictability, and policy stability, they gain the confidence to invest, expand, and compete globally.For India’s marine and seafood export sector, that confidence may prove more valuable than any short-term incentive.

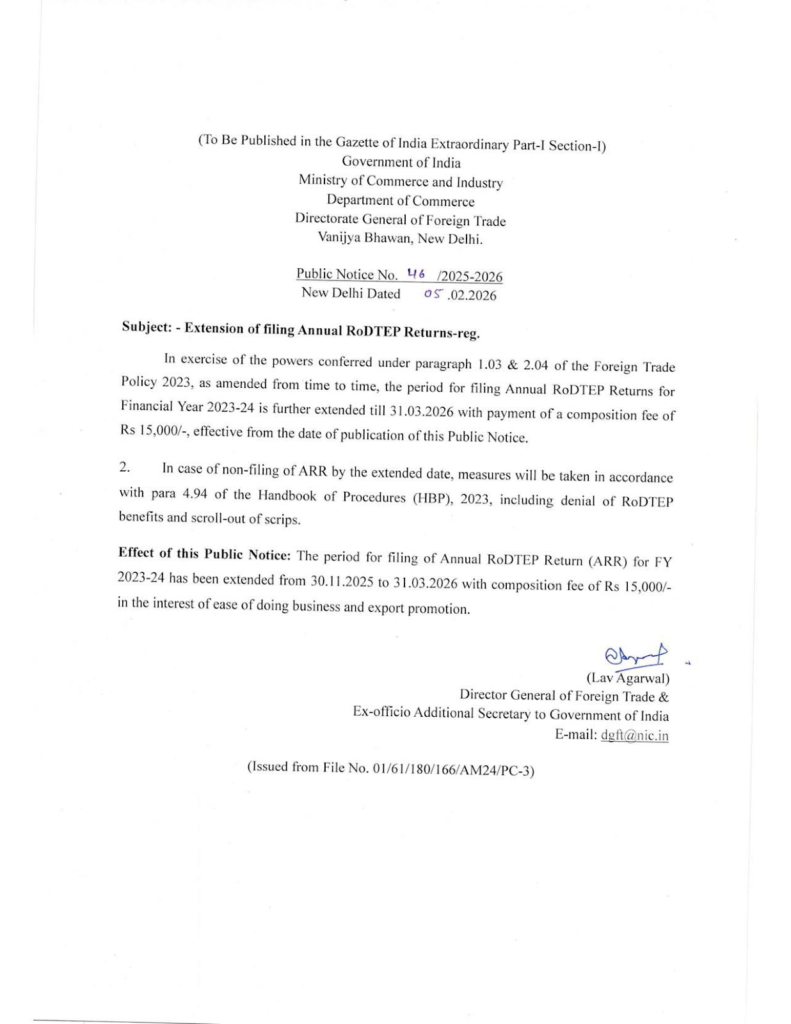
RoDTEP Annual Return (ARR) FY 2023–24 Extended to 31 March 2026: What Exporters Must Do Now

Sometimes, extensions feel like relief…

But in compliance, they also quietly remind us:
👉 “Don’t push it to the edge again.”

The Directorate General of Foreign Trade (DGFT) has extended the due date for filing the Annual RoDTEP Return (ARR) for FY 2023–24 to:

📅 31st March 2026
💰 With a composition fee of ₹15,000

What This Extension Means

Yes, the extension gives exporters some breathing room…

But it also comes with a clear warning:

❌ Failure to file even by the extended deadline may lead to:

  • Denial of RoDTEP benefits
  • Scroll-out of scrips

👉 In simple terms: your eligible incentives may be lost.

Why ARR Filing Is Critical

For many exporters, RoDTEP (Remission of Duties and Taxes on Exported Products) is not just an incentive:

👉 It is a real contributor to cash flow

Delaying ARR filing can result in:

  • Blocked or denied benefits
  • Financial impact on margins
  • Compliance risks during DGFT review

Why Exporters Delay ARR Filing

Common reasons include:

  • Pending audits
  • Incomplete reconciliations
  • Data gaps across systems
  • Complexity in cost and tax mapping

👉 But postponing only increases the risk.

ARR Is Not a Last-Day Compliance

Filing ARR involves more than just form submission. It requires:

  • Compilation of export data
  • Mapping of operational costs
  • Identification of embedded taxes
  • Proper reconciliation across records

👉 DGFT reviews the data submitted—so accuracy matters as much as timeliness.

Action Plan for Exporters

✔️ Start Data Compilation Now

  • Gather:
    • Export invoices
    • Shipping bill details
    • Cost and tax data

✔️ Reconcile Figures Carefully

  • Align:
    • Financial records
    • GST data
    • Export documentation

✔️ Avoid Last-Minute Filing

  • Early filing helps:
    • Identify errors
    • Reduce stress
    • Ensure compliance accuracy

✔️ Review Before Submission

  • Double-check:
    • Data consistency
    • Eligibility calculations
    • Supporting documentation

Key Reference

📄 Public Notice No. 46/2025–2026 dated 5th February 2026 issued by the Directorate General of Foreign Trade

Conclusion

The ARR filing extension is an opportunity—but also a responsibility.

👉 It gives you time to get it right
👉 But not an excuse to delay again

Final Thought 💬

In export compliance:

Incentives reward you…
But discipline protects you.Don’t let a pending ARR turn into a missed benefit.

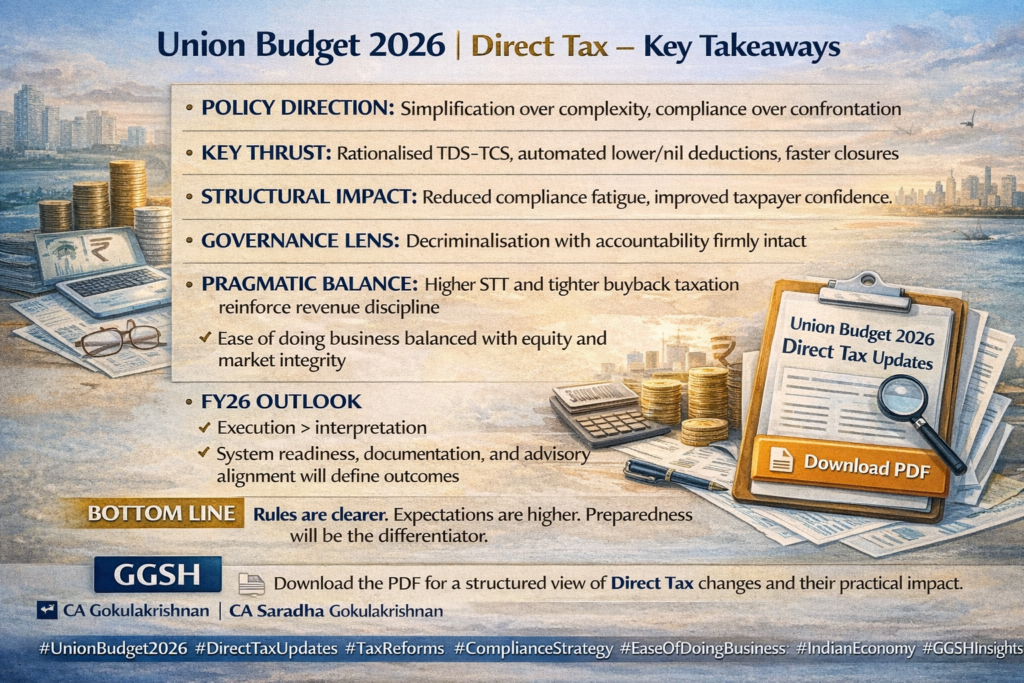
Union Budget 2026: Key Direct Tax Takeaways for Businesses & Tax Professionals

The Union Budget 2026 signals a clear shift in India’s direct tax policy framework. The government appears to be moving toward simplification of tax procedures, technology-driven compliance, and reduced litigation, while maintaining strong accountability mechanisms.

The policy direction reflects a balance between ease of doing business and disciplined tax governance, which will significantly influence how taxpayers, businesses, and professionals manage compliance in FY 2026 and beyond.

Policy Direction: Simplification Over Complexity

One of the central themes of the Union Budget 2026 direct tax proposals is the move toward simplified tax administration.

The objective is to reduce unnecessary procedural hurdles while encouraging voluntary compliance and transparency.

The reforms are guided by the policy framework set by the Ministry of Finance under the Government of India.

Key emphasis areas include:

  • Simplified tax rules
  • Reduced litigation and disputes
  • Greater reliance on digital systems
  • Faster resolution of taxpayer matters

This approach signals a shift from adversarial tax enforcement toward cooperative compliance.

Rationalised TDS and TCS Framework

A major structural reform under the budget involves the rationalisation of TDS (Tax Deducted at Source) and TCS (Tax Collected at Source) provisions.

The reforms aim to:

  • Reduce overlapping deduction and collection mechanisms
  • Streamline compliance obligations for businesses
  • Improve efficiency in tax reporting and credit matching

The initiative is expected to lower administrative burden on taxpayers while strengthening the overall tax credit ecosystem.

Automated Lower or Nil TDS Mechanisms

The budget also highlights increased automation in lower or nil TDS deduction approvals.

Through technology integration with the tax administration system operated by the Central Board of Direct Taxes, taxpayers may experience:

  • Faster processing of lower deduction certificate applications
  • Reduced manual intervention
  • Greater transparency in approval processes

This automation is intended to minimise delays and reduce compliance friction for businesses.

Faster Closure of Tax Matters

Another notable policy direction is the emphasis on speedier closure of tax proceedings and disputes.

This reflects the government’s commitment to:

  • Reduce long-pending tax litigation
  • Provide certainty to taxpayers
  • Improve overall tax administration efficiency

Quicker resolution of tax matters can significantly enhance taxpayer confidence and improve the investment environment.

Decriminalisation with Accountability

The budget also continues the trend toward decriminalisation of certain tax offences.

The objective is to ensure that minor procedural errors do not result in criminal prosecution, while maintaining strict action against serious cases of tax evasion or fraud.

This governance approach focuses on:

  • Encouraging voluntary compliance
  • Reducing fear-based enforcement
  • Maintaining accountability for deliberate violations

Market Discipline Through STT and Buyback Tax Changes

Despite the push toward simplification, the budget also reinforces revenue discipline and market integrity.

Measures such as:

  • Higher Securities Transaction Tax (STT)
  • Stricter buyback taxation provisions

demonstrate the government’s attempt to maintain equity in capital markets while protecting tax revenues.

These measures influence trading strategies, corporate restructuring, and investor decision-making.

FY 2026 Outlook: Execution Will Matter

For FY 2026, the focus shifts from interpreting tax rules to effectively implementing them.

Success under the new framework will depend on:

  • System readiness and digital integration
  • Strong documentation practices
  • Alignment between businesses and tax advisors
  • Timely compliance with updated procedures

Businesses that adapt early to the evolving technology-driven tax environment will have a clear advantage.

Union Budget 2026: What It Means for the Marine & Seafood Sector

Budgets are often read for headlines.
But industries read them for direction 🧭

For India’s marine and seafood sector, the Union Budget 2026 feels less like a routine announcement and more like a long-awaited signal of clarity across the ecosystem.

A Shift Towards End-to-End Visibility

The Budget indicates that policymakers are now looking at the sector holistically—not just exports, but:

  • Input costs
  • Fishing operations
  • Export frameworks
  • Compliance structures

👉 This end-to-end recognition is a major step forward for the industry.

Key Positive Signals for the Sector

🐡 Easing of Input Costs

  • Reduction in cost pressures helps:
    • Improve margins
    • Increase competitiveness in global markets

🐡 Clarity in Deep-Sea Fishing Policies

  • Better regulatory clarity supports:
    • Long-term planning
    • Investment in infrastructure and vessels

🐡 Predictability in Export Treatment

  • Stable and consistent export framework ensures:
    • Fewer disputes
    • Smoother compliance
    • Faster decision-making

Why This Matters More Than It Seems

At first glance, these changes may not appear “dramatic.”

But in reality:

👉 Businesses don’t just benefit from cost savings
👉 They gain confidence to plan ahead

And in industries like seafood, where:

  • Seasonality matters
  • Logistics are complex
  • Global competition is intense

👉 Planning always beats firefighting.

The Real Impact: Reducing Long-Standing Uncertainty

For years, the sector has dealt with:

  • Ambiguity in tax treatment
  • Compliance inconsistencies
  • Policy interpretation challenges

The Union Budget 2026 addresses this—not by flashy incentives, but by:

👉 Removing uncertainty

Clarity vs Incentives: What Truly Drives Growth?

There’s a subtle but powerful takeaway here:

  • Incentives excite businesses
  • Clarity sustains them

When policies are:

  • Clear
  • Predictable
  • Consistent

👉 Businesses invest more confidently
👉 Growth becomes stable—not reactive

What This Means for Industry Stakeholders

✔️ Exporters

  • Better planning of shipments and pricing
  • Reduced compliance risks

✔️ Processors & Manufacturers

  • Improved cost control
  • Greater operational efficiency

✔️ Investors

  • Increased confidence in sector stability
  • Better long-term visibility

Conclusion

The Union Budget 2026 may not have introduced dramatic reforms for the marine and seafood sector—but it delivers something far more valuable:

👉 Clarity, consistency, and confidence

Final Thought 💬

In a sector driven by cycles, risks, and global demand:

👉 It’s not just about catching the next opportunity
👉 It’s about knowing the waters are finally predictable

Because in the long run:Incentives may attract growth…
But clarity is what sustains it. 💪🏼

Purchases from Unregistered Persons (URP) Under GST: Simple in Theory, Risky in Practice

Purchasing from Unregistered Persons (URPs) may look like routine procurement…

But in reality, these transactions can quietly trigger multiple GST compliance risks—especially as volumes increase or during audits.

What seems simple on paper often becomes complex in execution.

Why URP Transactions Need Attention

Many businesses treat URP purchases as:

  • Low-risk
  • Operationally convenient
  • Easy to manage

However, these transactions can lead to:

  • Reverse Charge Mechanism (RCM) exposure
  • E-way bill compliance challenges
  • Documentation gaps
  • Reporting mismatches

👉 The risk becomes more visible during assessments and audits.

Key GST Implications on URP Purchases

1. Reverse Charge Mechanism (RCM)

When purchasing from URPs:

  • Tax liability shifts to the recipient (buyer)
  • Applicable under notified categories and scenarios

👉 Businesses must:

  • Identify RCM applicability
  • Pay GST in cash
  • Report correctly in returns

2. Self-Invoicing & Payment Voucher

Under RCM:

  • Buyer must issue a self-invoice
  • Payment voucher must be generated at the time of payment

👉 Timelines and accuracy are critical for compliance.

3. E-Way Bill Responsibility

When the supplier is unregistered:

  • The recipient may be responsible for generating the e-way bill

👉 This depends on:

  • Movement of goods
  • Transaction structure
  • Threshold limits

4. Inter-State vs Intra-State Impact

URP transactions require careful classification:

  • Inter-State → IGST implications
  • Intra-State → CGST + SGST

👉 Misclassification can lead to:

  • Incorrect tax payment
  • Reporting errors

5. Return Reporting Complexity

URP transactions must be accurately reported in:

  • GSTR-3B (RCM liability & ITC claim)
  • GSTR-9 (annual consolidation)
  • GSTR-9C (reconciliation & audit)

👉 Errors here often trigger notices.

The Hidden Risk: Documentation Gaps

Unlike registered vendors, URPs may not provide:

  • GST-compliant invoices
  • Structured documentation

👉 This increases reliance on internal controls and records.

URP Procurement Checklist: What You Should Follow

To manage URP risks effectively, businesses should adopt a structured workflow:

✔️ Vendor Due Diligence (KYV – Know Your Vendor)

  • Verify identity and business background

✔️ PAN & GST Status Verification

  • Confirm unregistered status
  • Ensure correct classification

✔️ Transaction Structuring

  • Identify:
    • Nature of supply
    • Place of supply
    • Tax applicability

✔️ RCM Compliance

  • Raise self-invoice
  • Issue payment voucher
  • Pay tax within timelines

✔️ E-Way Bill Compliance

  • Determine responsibility clearly
  • Generate e-way bill where required

✔️ Return Reporting

  • Ensure accurate disclosure in:
    • GSTR-3B
    • GSTR-9
    • GSTR-9C

✔️ Record Retention & Audit Readiness

  • Maintain:
    • Supporting documents
    • Internal approvals
    • Reconciliation records

Why a Checklist Approach Works

A structured checklist helps:

  • Procurement teams ask the right questions upfront
  • Finance teams ensure accurate tax compliance
  • Businesses avoid downstream disputes and penalties

👉 Most importantly, it ensures compliance without slowing operations.

Conclusion

Purchases from URPs are not inherently risky—but unmanaged URP transactions are.

The key lies in:

  • Strong internal processes
  • Clear documentation
  • Timely compliance actions

Final Thought 💬

In GST:👉 It’s not the transaction that creates risk…
👉 It’s the lack of structure around it